
Direct Answer
A Netherlands payment gateway lets domestic and cross-border merchants collect EUR online across Dutch bank accounts, cards, and wallets. According to the Dutch Payments Association (2025 data published March 2026), iDEAL accounts for 71% of the 347 million Dutch online purchases (€35.7 billion), followed by credit cards (8%), direct debits (5%), and Klarna (4%). Since January 2026, checkouts display co-branded iDEAL | Wero, with 12 Dutch banks launching Wero e-commerce on 26 October 2026 ahead of full cutover by end of 2027.
Why the Netherlands Requires an iDEAL | Wero-First Payment Stack
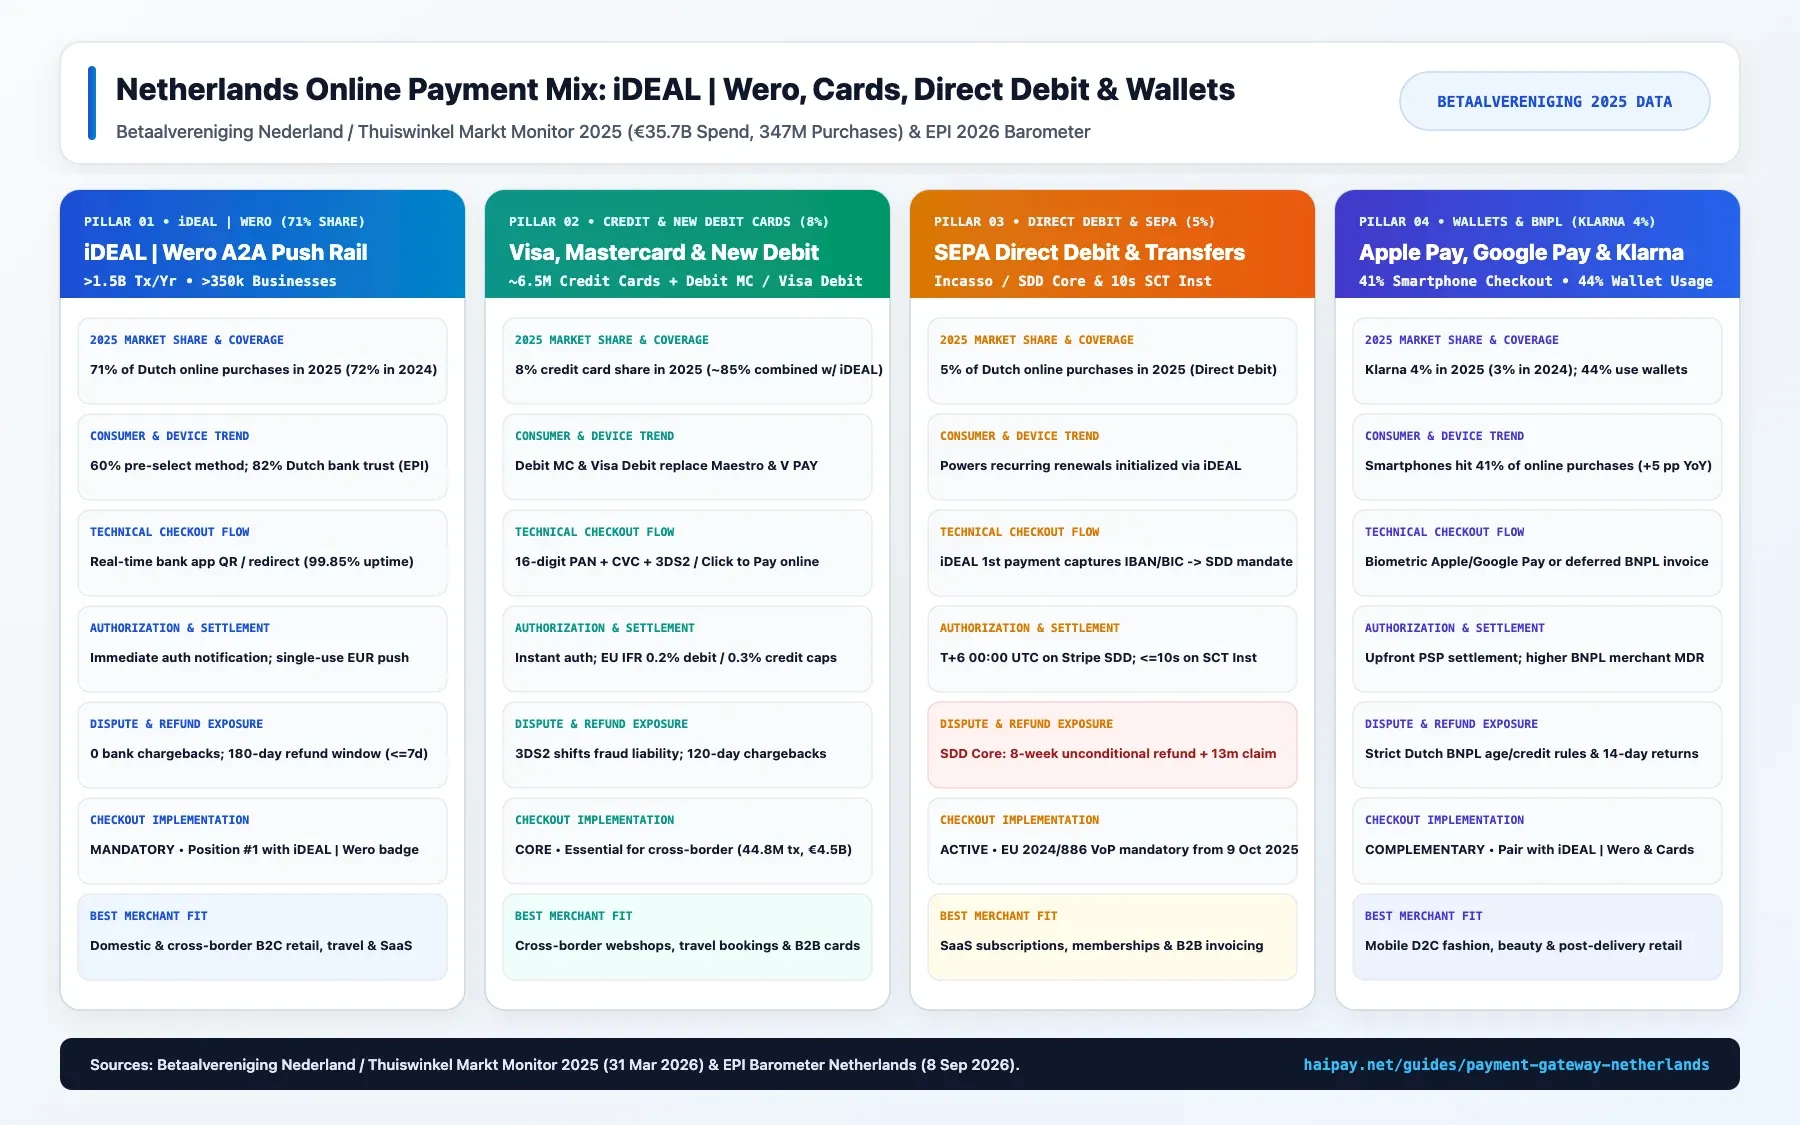
The Netherlands runs one of Europe's most concentrated account-to-account (A2A) e-commerce markets. According to the Dutch Payments Association (Betaalvereniging Nederland) 2025 report (published 31 March 2026), 14 million Dutch shoppers spent €35.7 billion across 347 million online purchases. Domestic volume reached 302.2 million orders. Cross-border purchases at foreign webshops rose 9% to 44.8 million (€4.5 billion, or 13% of spend).
Card-only checkouts lose Dutch buyers before authorization even starts. Official Betaalvereniging Nederland online payment statistics show that 60% of Dutch shoppers pick their payment method before reaching the checkout page. In 2025, iDEAL captured 71% of Dutch online purchases, compared with 72% in 2024. Credit cards held 8% across roughly 6.5 million cards, direct debits held 5%, and Klarna reached 4% (up from 3%).
Payment Rail | 2025 NL Share | Authentication & Flow | Settlement & Dispute Rules |
|---|---|---|---|
iDEAL | Wero (A2A) | 71% (72% in 2024) | Dutch bank app QR/redirect with 2FA SCA (99.85% uptime) | Immediate auth; 0 chargebacks; 180-day refund window (<=7d pending) |
Credit & New Debit | 8% credit (~85% w/ iDEAL) | Visa, Mastercard, Debit MC & Visa Debit with EMV 3DS2 | Instant auth; IFR 0.2% debit / 0.3% credit caps; 120-day disputes |
SEPA Direct Debit | 5% of purchases | IBAN pull mandate (often seeded via iDEAL) + Oct 2025 VoP | T+6 on Stripe; 8-week unconditional refund + 13-month claim |
Klarna & Wallets | 4% Klarna; 44% wallets | BNPL invoice or biometric Apple/Google Pay (41% mobile) | Upfront PSP settlement; 14-day return right & Dutch BNPL checks |
Source: Betaalvereniging Nederland / Thuiswinkel Markt Monitor 2025 (31 March 2026) and EPI Barometer Netherlands (8 September 2026).
Debit Mastercard, Visa Debit & Smartphone Wallet Growth
Two shifts are reshaping the remaining 29% of Dutch checkouts in 2026. Smartphones generated 41% of online purchases in 2025 (up 5 points from 2024), while desktop share dropped from 49% to 45%. Meanwhile, Dutch banks are replacing Maestro and V PAY cards with Debit Mastercard and Visa Debit cards. These new debit cards support 16-digit PAN entry, CVC codes, Click to Pay, and Apple Pay or Google Pay.
The EPI 2026 Barometer for the Netherlands (published 8 September 2026 across 1,061 respondents) shows why bank rails dominate. Exactly 82% of Dutch consumers trust their bank for payment security, versus 54% for card schemes and 49% for Big Tech. Today, 44% use a smartphone wallet, and iDEAL plus cards cover roughly 85% of e-commerce volume.
Cross-Border Entity Onboarding & Dutch Storefront Compliance (KVK, BTW & EAA)
Foreign merchants often ask whether they must form a local Dutch private limited company (Besloten Vennootschap, or BV) to accept iDEAL | Wero. When you onboard through a licensed international payment gateway, a local Dutch BV or KVK entity is not required.
With HaiPay's Europe & Americas local payment gateway, companies in the US, the UK, Hong Kong, Singapore, or any EEA country activate iDEAL | Wero, SEPA, and cards under one contract. Standard Know Your Business (KYB) review verifies incorporation documents, 25%+ Ultimate Beneficial Owners (UBOs), corporate bank accounts, and storefront compliance.
- Statutory KVK or Home Registration ID: Under Dutch law and Stripe's iDEAL merchant rules, your website must display your KVK number or your home country's official company registration number.
- Dutch BTW (21% / 9%) & 14-Day Returns: B2C prices must appear in EUR inclusive of Dutch VAT (BTW, 21% standard and 9% reduced rate), filed via EU OSS. Terms must state the 14-day withdrawal period (herroepingsrecht).
- European Accessibility Act (EAA) UI: Since June 2025 under EU Directive 2019/882, Dutch checkouts must provide keyboard navigation, ARIA labels, and accessible error recovery.
- Multi-Country European Expansion: Pair Dutch iDEAL | Wero with adjacent payment stacks in Germany, France, and the United Kingdom through one integration.
iDEAL 2.0 Architecture & the 2026–2028 Wero Migration Roadmap
Launched in 2005, iDEAL processes over 1.5 billion transactions annually (over 1.47 billion in 2024, averaging 4 million daily payments and peaking at 6.3 million on Black Friday). More than 350,000 businesses and 210,000 webshops accept the rail. Per Betaalvereniging Nederland 2025 key figures, Dutch mobile banking hit 99.85% availability and internet banking reached 99.88% in 2025 under a 2-hour legal outage limit.
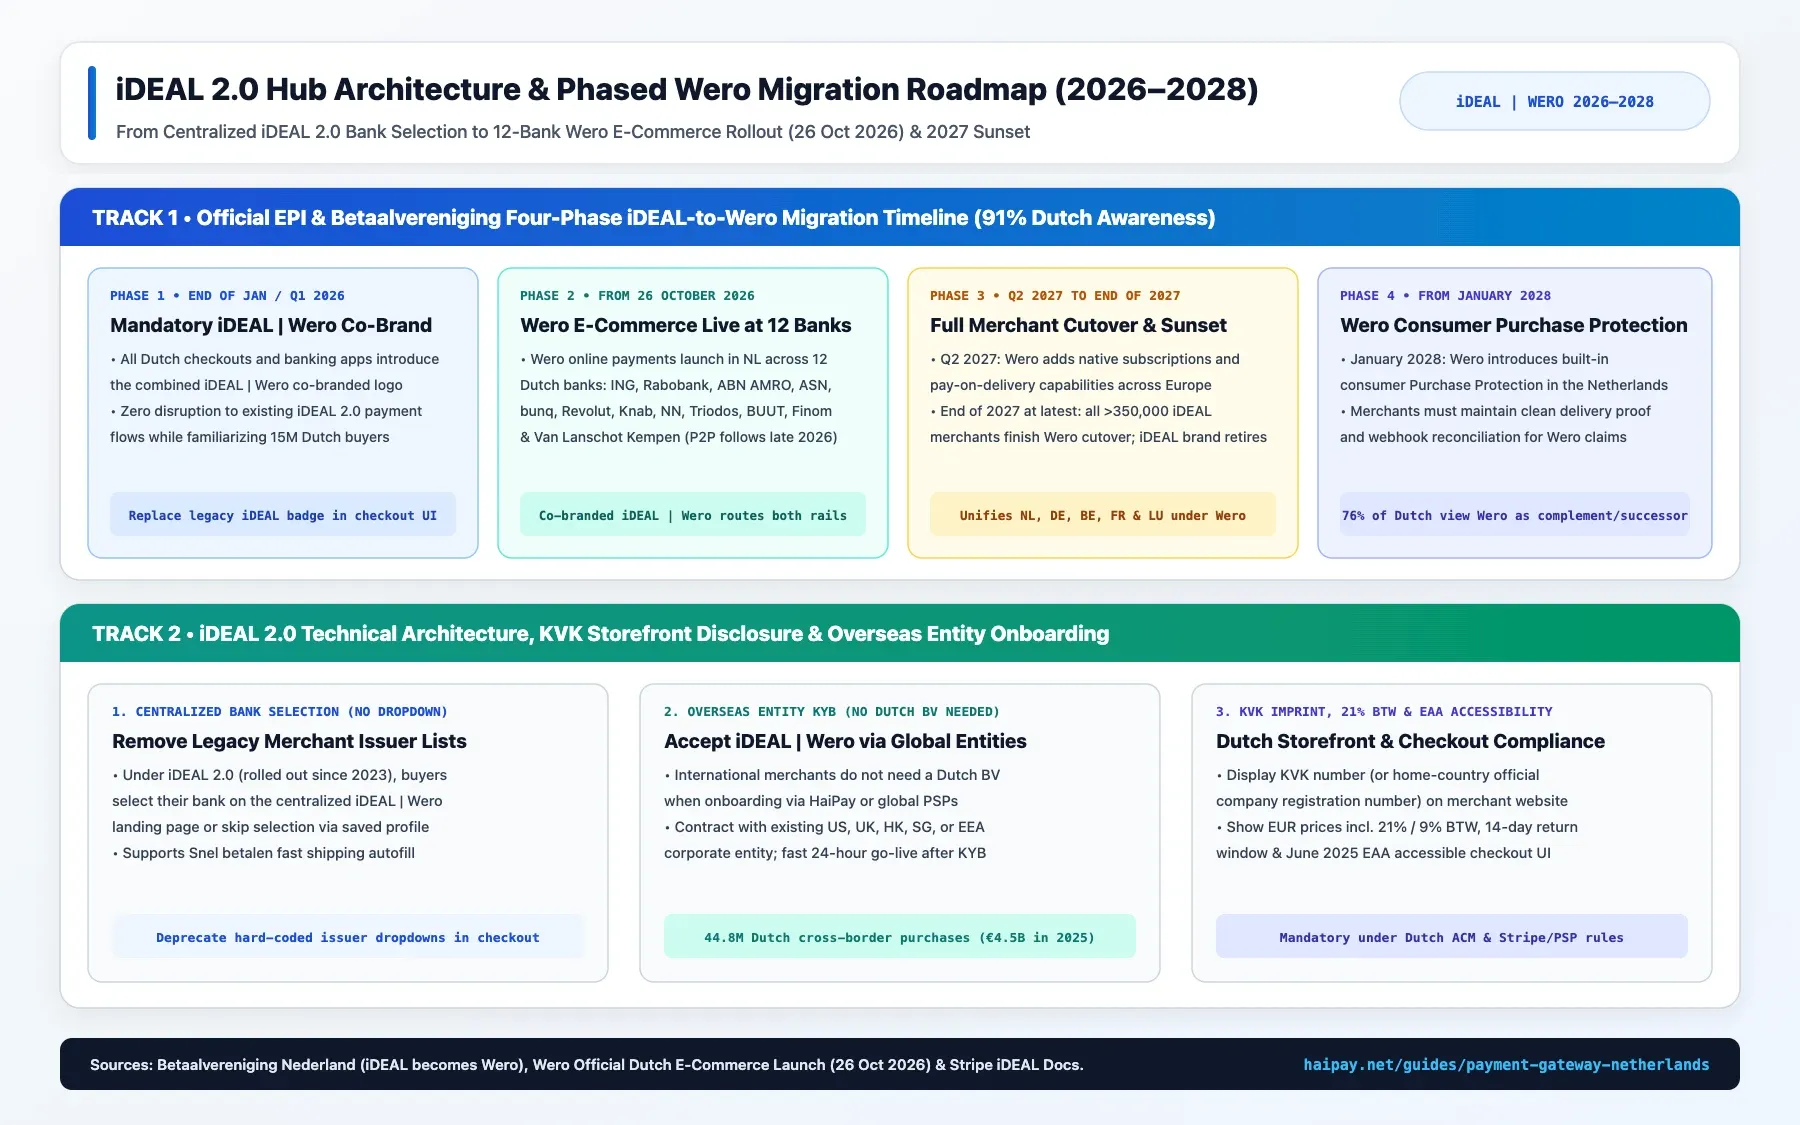
Starting in 2023, iDEAL rolled out its iDEAL 2.0 hub architecture before the European Payments Initiative (EPI) acquired iDEAL and Payconiq on 31 October 2023. Merchants must remove legacy checkout bank dropdown lists. Buyers now pick their bank on the centralized iDEAL | Wero page or skip selection via saved profiles and Snel betalen fast checkout.
Window | Milestone & Brand State | Participating Banks & Scope | Merchant Action Required |
|---|---|---|---|
Jan / Q1 2026 | iDEAL | Wero Co-Brand | All Dutch banks, PSPs & >350,000 merchants | Show co-branded iDEAL | Wero badge; drop bank dropdowns |
From 26 Oct 2026 | Wero E-Commerce Live | 12 banks: ABN AMRO, ASN, bunq, BUUT, Finom, ING, Knab, NN, Rabobank, Revolut, Triodos, Van Lanschot Kempen | Process iDEAL and Wero via the co-branded gateway rail |
Q2–End 2027 | Full Merchant Cutover | ~15M Dutch buyers; webshops across NL, DE, BE, FR & LU | Finish Wero cutover by end of 2027 before iDEAL retires |
From Jan 2028 | Purchase Protection | All Dutch Wero e-commerce transactions | Sync delivery proof webhooks for Wero buyer protection claims |
Source: Betaalvereniging Nederland (iDEAL becomes Wero) and Wero Official Dutch E-Commerce Announcements (accessed November 2026).
Key Cutover Dates from October 2026 to January 2028
As outlined in Betaalvereniging Nederland's iDEAL-to-Wero guide and Wero's rollout schedule, the four-phase transition prevents checkout drop-off. Co-branding started at the end of January 2026. By September 2026, EPI's Barometer found that 91% of Dutch consumers knew Wero and 76% viewed it as a replacement or complement.
From 26 October 2026, 12 Dutch banks and institutions enable Wero e-commerce, with P2P transfers following in late 2026. Native Wero subscriptions and pay-on-delivery launch in Q2 2027. All iDEAL merchants complete cutover by the end of 2027 at the latest, and Wero adds Dutch consumer Purchase Protection in January 2028.
Gateway Pricing, EEA Interchange Caps & Cross-Border FX Economics
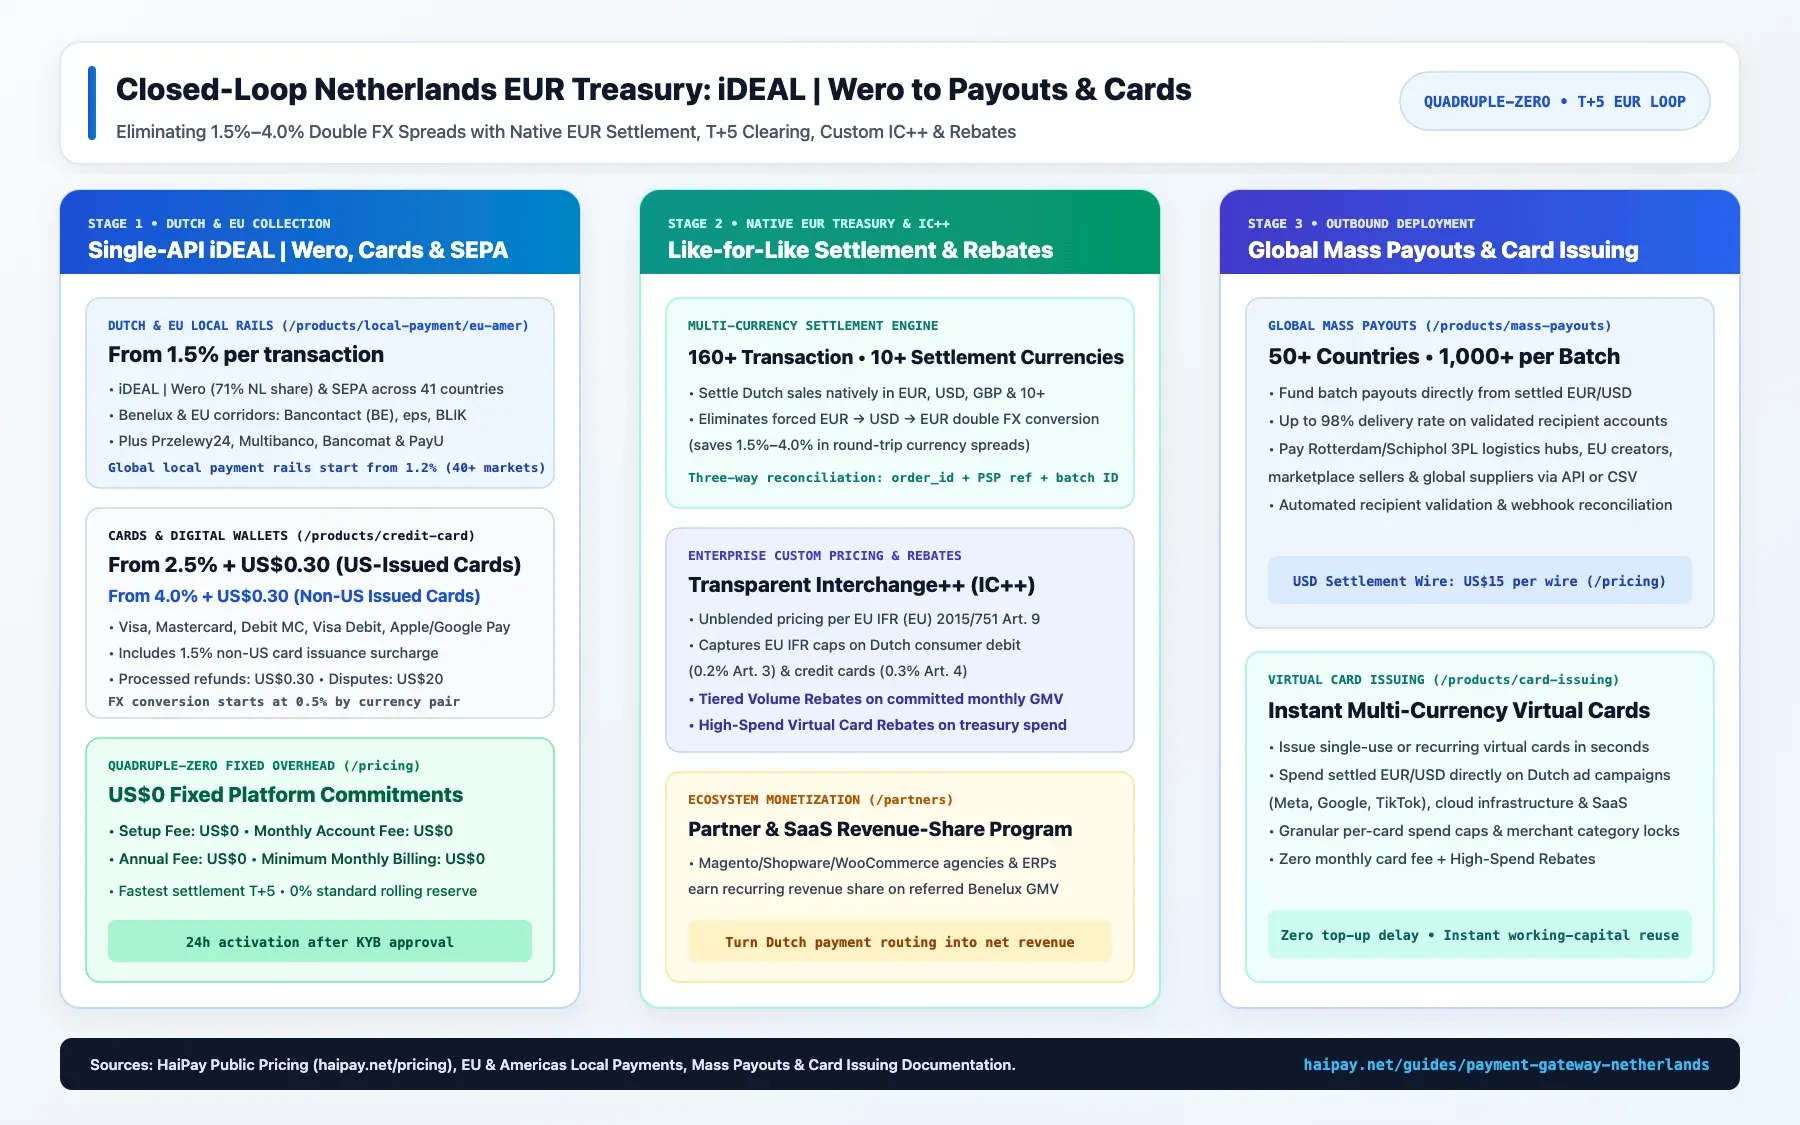
Benchmarking Dutch payment gateway pricing requires separating A2A push transfers from card acquiring tiers. Under Articles 3 and 4 of Regulation (EU) 2015/751 (Interchange Fee Regulation), EEA consumer debit interchange is capped at 0.2% and consumer credit interchange is capped at 0.3%. Article 9 also grants merchants the right to request unblended Interchange++ (IC++) fee disclosure.
Those statutory caps exclude corporate cards and non-EEA cards, where self-serve PSPs add cross-border surcharges. On Stripe's Netherlands pricing schedule, iDEAL | Wero costs €0.29 per payment (while historical Dutch market tiers on Stripe's iDEAL overview span €0.20 to €0.75). Standard EEA cards cost 1.5% + €0.25, premium EEA cards cost 2.8% + €0.25, UK cards cost 2.5% + €0.25, and international cards cost 3.15% + €0.25 (plus +2% FX).
Fee Dimension | EU Baseline | Stripe NL Schedule | HaiPay Schedule & Enterprise Options |
|---|---|---|---|
iDEAL | Wero & EU Rails | EUR synchronous push | €0.29 iDEAL (range €0.20–€0.75); SDD <=€10k | From 1.5% on EU & Americas local rails (from 1.2% in 40+ markets) |
Consumer & Int'l Cards | 0.2% debit / 0.3% credit | 1.5%+€0.25 EEA; 2.8%+€0.25 prem; 3.15%+€0.25 int'l | From 2.5% + US$0.30 (US); From 4.0% + US$0.30 (non-US) on Card Acquiring |
FX & Multi-Currency | ECB reference rate rules | +2% FX fee; 1% multi-currency payout fee | FX from 0.5%; native EUR, USD, GBP & 10+ settlement currencies |
Refunds, Disputes & Wires | 0 bank disputes on iDEAL | €20.00 dispute fee on cards and SDD | US$0.30 refund; US$20 dispute; US$15 per USD wire |
Fixed Fees & Reserves | IFR Art. 9 IC++ right | Blended self-serve; custom via sales | US$0 setup/monthly/annual/min, 0% standard reserve & custom IC++ |
Source: Regulation (EU) 2015/751, Stripe Netherlands Pricing (accessed November 2026), and HaiPay Public Pricing (/pricing).
When modelling Dutch unit economics across merchant account fees and rolling reserve policies, finance teams should compare fixed-fee A2A iDEAL | Wero pricing against ad-valorem card rates. On high-ticket Dutch orders, flat-fee iDEAL | Wero push transfers avoid percentage interchange, whereas Debit Mastercard and Visa Debit benefit from EEA 0.20% debit and 0.30% credit caps. On HaiPay's /pricing schedule, qualified merchants pay US$0 setup, monthly, annual, and minimum monthly fees with a 0% standard rolling reserve.
PSD2 SCA, 180-Day Push Refunds & SEPA Direct Debit Recall Controls
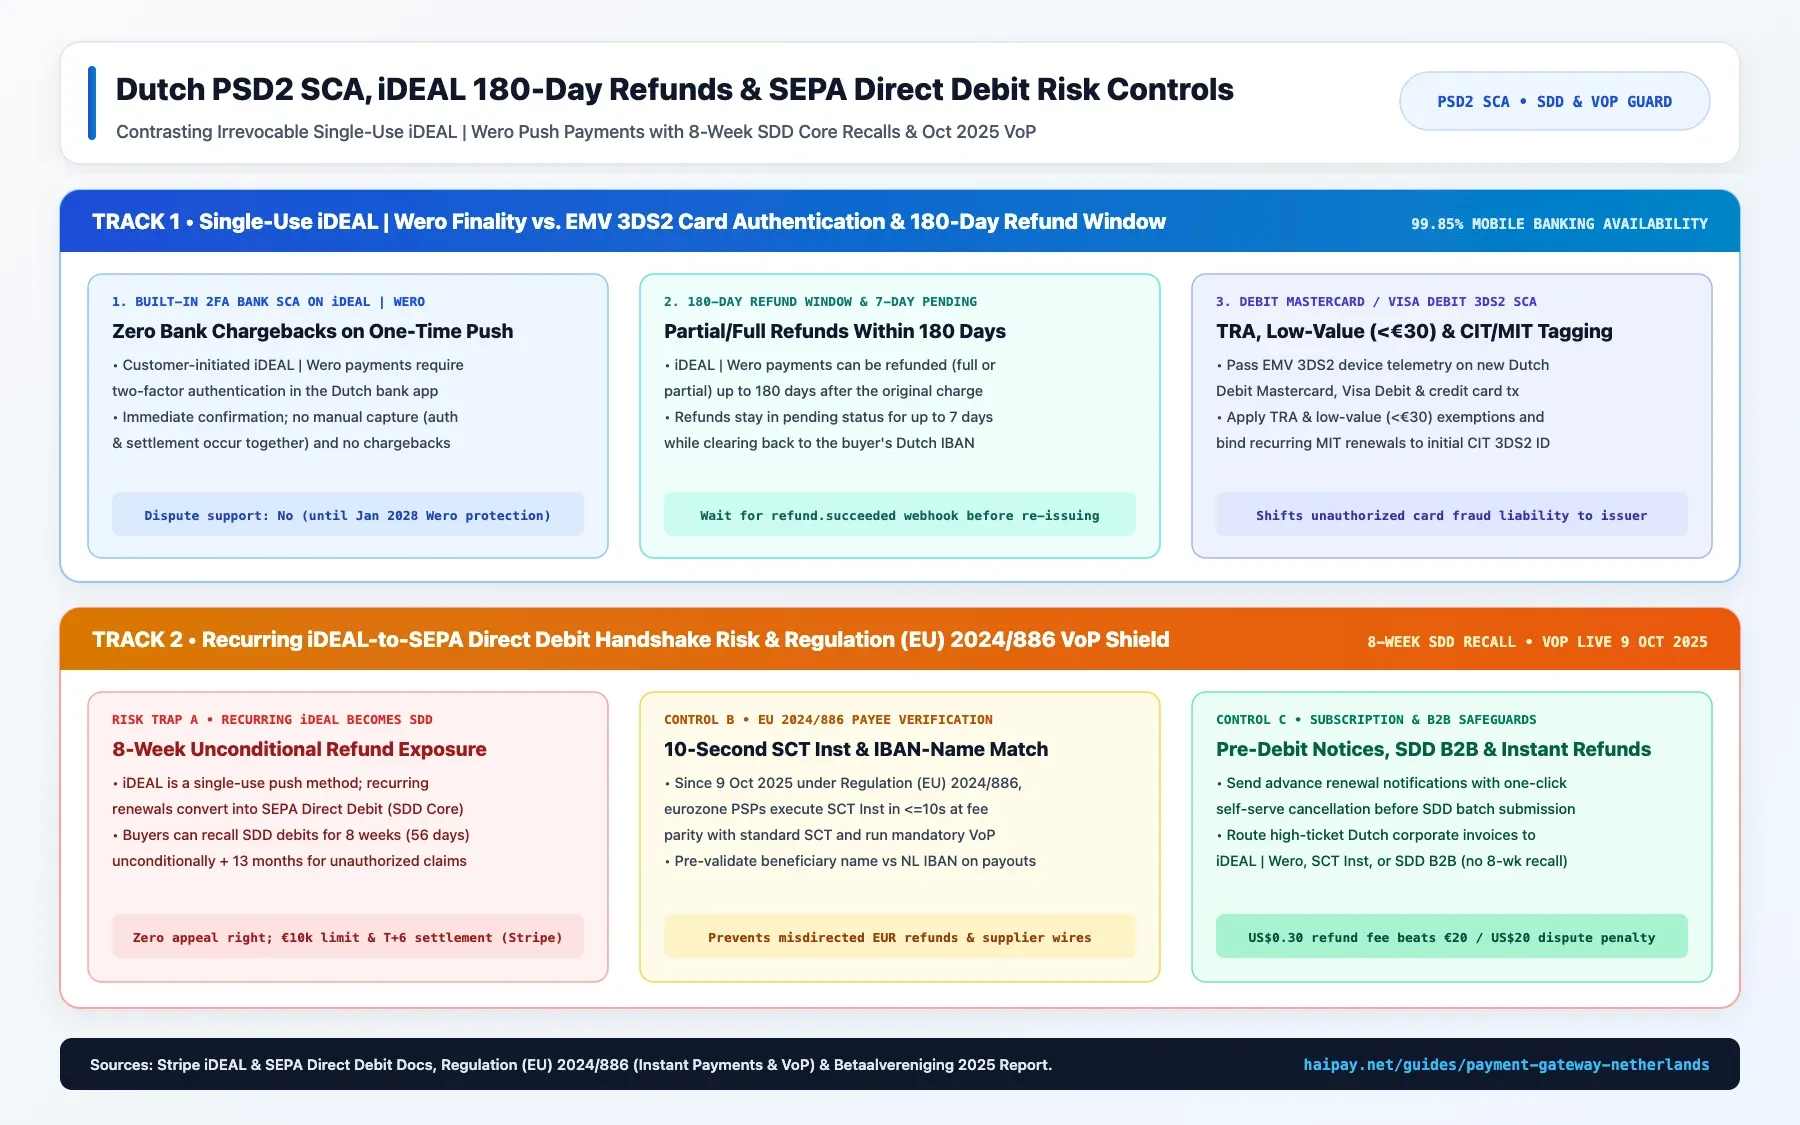
Risk management in the Netherlands depends on separating irrevocable push payments from revocable pull mandates. Per Stripe's iDEAL documentation, every single-use iDEAL | Wero payment is authenticated via two-factor Strong Customer Authentication (2FA SCA) inside the customer's Dutch banking app.
Authorization and capture occur simultaneously on iDEAL | Wero, so manual capture is not supported. Single-use iDEAL payments carry zero bank chargebacks (Dispute support: No) prior to Wero's January 2028 Purchase Protection rollout. Merchants can refund payments in full or in part for up to 180 days, though refunds stay pending for up to 7 days while clearing.
- Ring-Fence Recurring iDEAL-to-SDD Renewals. Recurring billing uses an initial iDEAL | Wero payment to capture a verified IBAN and BIC and create a SEPA Direct Debit (SDD Core) mandate. Under EPC SDD Core rules—covered in our SEPA Payments Guide—buyers hold an 8-week (56-day) unconditional refund right and a 13-month unauthorized claim window.
- Send Renewal Alerts & Automate 14-Day Refunds. Send pre-debit notices and offer instant self-serve refunds (US$0.30 on HaiPay). This stops buyers from tapping the 1-click recall button in ING, Rabobank, or ABN AMRO apps (€20 / US$20 dispute fee).
- Adopt Regulation (EU) 2024/886 VoP. Under Regulation (EU) 2024/886 and the ECB SEPA Instant framework, eurozone PSPs provide 10-second SEPA Instant transfers (SCT Inst) at fee parity with standard SCT. Mandatory Verification of Payee (VoP) IBAN-name checks also took effect on 9 October 2025.
- Configure EMV 3DS2 Exemptions on New Dutch Debit Cards. Pass device telemetry on Debit Mastercard, Visa Debit, and credit cards to claim frictionless TRA and low-value (<€30) exemptions. Link recurring MIT renewals to the initial CIT 3DS2 ID.
Closed-Loop EUR Settlement, Three-Way Reconciliation & Outbound Payouts
For cross-border sellers, the biggest margin leak in the Netherlands is forced double currency conversion. Many gateways convert Dutch EUR sales into USD or HKD at settlement. When the merchant later converts funds back into EUR to pay Rotterdam 3PLs or European suppliers, round-trip FX spreads cost 1.5% to 4.0%.
By pairing cross-border payment collection with a multi-currency merchant account, HaiPay lets overseas merchants collect across 160+ transaction currencies. Dutch iDEAL | Wero and card proceeds settle natively in EUR, USD, GBP, and 10+ currencies on a T+5 cycle (or T+1 across 8 local markets). Finance teams can then route settled EUR directly into Global Mass Payouts across 50+ countries (1,000+ recipients per batch with up to 98% delivery rates on validated supplier accounts).
Downloadable 12-Point Dutch Launch & EUR Reconciliation Checklist
To keep accounting teams audit-ready across T+5 EUR batches, 180-day iDEAL | Wero refunds, and T+6 SEPA Direct Debit clearings, download our Netherlands Payment Gateway Launch, iDEAL-to-Wero & EUR Reconciliation Checklist (CSV). The 12-point template maps checkout order IDs, PSP references, and IBAN batch IDs across every Dutch rail.
How to Select a Netherlands Payment Gateway by Business Model
Selecting the right Dutch payment gateway depends on your average order value (AOV), recurring billing model, and supplier payout currency. Use the matrix below to match your business model to the optimal checkout and treasury configuration.
Business Model | Primary Rail #1 | Secondary Backup & Wallets | Treasury & Risk Priority |
|---|---|---|---|
D2C E-Commerce | iDEAL | Wero (71% share; centralized hub) | Debit MC, Visa Debit, Apple/Google Pay & Klarna | Show KVK / home reg ID; settle EUR to fund Dutch 3PLs |
SaaS & Subscriptions | iDEAL | Wero -> SDD Core renewal | Visa / MC with 3DS2 CIT + MIT network tokens | Send pre-debit notices; automate refunds vs 8-week recall |
B2B Wholesale | iDEAL | Wero, 10s SCT Inst, or SDD B2B | Corporate Visa / MC with custom IC++ pricing | Use SDD B2B (0 recall) and Oct 2025 VoP IBAN checks |
EU Marketplaces | Single API: iDEAL | Wero, Bancontact & SEPA | Apple Pay, Google Pay & EEA debit/credit cards | Route settled EUR into Mass Payouts & Dutch 3PLs |
Source: HaiPay Dutch & European Payment Architecture Playbook (2026).
Ready to accept iDEAL | Wero, Debit Mastercard, Visa Debit, Apple Pay, Google Pay, and SEPA in the Netherlands without forming a local Dutch BV? Contact HaiPay's payment architects to verify your KVK or home-country registration display, prepare for the 2026–2027 Wero cutover, and activate native T+5 EUR settlement.
Sources & Official Regulatory References
- Betaalvereniging Nederland — Thuiswinkel Markt Monitor 2025 (31 March 2026). 2025 Dutch online spend (€35.7B), purchases (347M), cross-border orders (44.8M / €4.5B), mobile share (41%), and payment split (71% iDEAL, 8% credit cards, 5% direct debits, 4% Klarna).
- Betaalvereniging Nederland — Online Payments, Cards & 2025 Key Figures. ~6.5M credit cards, ~85% combined iDEAL + card share, 60% pre-checkout method selection, Debit Mastercard / Visa Debit rollout, and 99.85% mobile banking uptime.
- Betaalvereniging Nederland & Wero — iDEAL Becomes Wero & 26 October 2026 Launch. Four-phase roadmap: Jan 2026 iDEAL | Wero co-brand, 26 Oct 2026 Wero e-commerce across 12 Dutch banks, end-2027 cutover, and Jan 2028 Purchase Protection.
- European Payments Initiative (EPI) — EPI Barometer Netherlands (8 September 2026). Survey of 1,061 Dutch respondents showing 82% bank trust, 44% mobile wallet usage, 91% Wero awareness, and 76% Wero adoption intent.
- EUR-Lex — Regulation (EU) 2015/751 (IFR) & Regulation (EU) 2024/886 (Instant Payments & VoP). 0.2% EEA debit and 0.3% credit interchange caps, Article 9 IC++ transparency, and 9 October 2025 10s SCT Inst and VoP mandates.
- Stripe Documentation & Netherlands Pricing — iDEAL & SEPA Direct Debit Rules. EUR-only presentment, KVK or home-country company registration display, 180-day refund window (<=7d pending), SDD Core 8-week / 13-month recall rules, and NL fee tiers.
FAQ
According to the Dutch Payments Association (Betaalvereniging Nederland) and the Thuiswinkel Markt Monitor 2025 (published 31 March 2026), iDEAL (co-branded as iDEAL | Wero since January 2026) is the leading online payment method in the Netherlands, capturing 71% of all 347 million online purchases (€35.7 billion total spend). Credit cards rank second at 8% (across roughly 6.5 million circulating credit cards), followed by SEPA direct debits at 5% and Klarna at 4%, while Dutch banks are actively replacing legacy Maestro and V PAY debit cards with online-enabled Debit Mastercard and Visa Debit cards.
Following the European Payments Initiative (EPI) acquisition of iDEAL, the migration runs in four official phases: (1) since the end of January 2026, checkouts display the co-branded iDEAL | Wero logo; (2) from 26 October 2026, Wero e-commerce goes live across 12 participating Dutch banks (ABN AMRO, ASN Bank, bunq, BUUT, Finom, ING, Knab, Nationale-Nederlanden, Rabobank, Revolut, Triodos Bank, and Van Lanschot Kempen); (3) subscriptions and pay-on-delivery launch in Q2 2027, and all merchants complete migration to Wero by the end of 2027 at the latest, after which the standalone iDEAL brand retires; and (4) in January 2028, Wero introduces native consumer Purchase Protection in the Netherlands.
Yes. Cross-border merchants incorporated in the United States, the United Kingdom, Hong Kong, Singapore, or another EEA Member State do not need to form a local Dutch BV to accept iDEAL | Wero. By onboarding through HaiPay's single API (/products/local-payment/eu-amer) or a licensed international PSP, overseas entities pass standard corporate KYB verification and display either their Dutch KVK number or the official company registration number from their home country on their website.
Single-use iDEAL | Wero payments are customer-initiated bank push transfers authenticated via two-factor Strong Customer Authentication (2FA SCA) inside the customer's banking app, so they carry zero bank chargebacks (Dispute support: No) prior to Wero's January 2028 Purchase Protection rollout. Merchants can issue full or partial refunds within 180 days of the original charge, and refunded funds may remain in a pending state for up to 7 days while clearing back to the buyer's IBAN.
Because iDEAL is a single-use push rail, recurring subscriptions use an initial iDEAL | Wero payment to authenticate the customer and capture their verified IBAN and BIC, which then creates a SEPA Direct Debit (SDD Core) mandate for subsequent renewals (up to Wero's native subscription rollout in Q2 2027). Merchants must monitor SDD Core risk closely because eurozone consumers have an 8-week (56-day) unconditional no-questions-asked refund right and a 13-month claim window for unauthorized debits.
Under the EU Interchange Fee Regulation (EU) 2015/751, EEA consumer debit interchange is capped at 0.2% and consumer credit interchange at 0.3%. On self-serve gateways such as Stripe Netherlands, iDEAL costs €0.29 per payment (historical market range €0.20–€0.75), standard EEA cards cost 1.5% + €0.25, UK cards cost 2.5% + €0.25, and international cards cost 3.15% + €0.25 (plus +2% FX). On HaiPay (/pricing), European local payment rails start from 1.5%, card acquiring starts from 2.5% + US$0.30 (US cards via a US entity) or from 4.0% + US$0.30 (non-US cards), with US$0 setup, monthly, annual, and minimum monthly fees plus unblended IC++ pass-through pricing for high-volume EEA card traffic.
Double FX conversion occurs when a payment gateway forces Dutch EUR checkout revenue into USD or HKD at settlement and the merchant converts funds back into EUR to pay Rotterdam 3PL logistics hubs or European suppliers, losing 1.5% to 4.0% in currency spreads. With HaiPay, merchants collect in 160+ currencies, settle natively in EUR, USD, GBP, and 10+ currencies on a T+5 cycle (0% standard rolling reserve), and route settled EUR directly into Global Mass Payouts across 50+ countries without forced currency conversion.

Related HaiPay surfaces
Explore the payment stack
Guide
SEPA Payments Guide: SCT, Instant & Direct Debit
Deep dive into SCT, 10-second SCT Inst, SDD Core 8-week refund rules, SDD B2B finality, and Regulation (EU) 2024/886 VoP across 41 countries.
Guide
Payment Gateway Germany: SEPA, Cards & Local Rails
Compare the Netherlands' 71% iDEAL | Wero A2A checkout mix against Germany's EHI 2025 invoice, PayPal, and SEPA Direct Debit landscape.
Guide
Payment Gateway France: CB Cards, SEPA & Wallets
Explore France's Cartes Bancaires (CB) co-badged card routing, Apple Pay and PayPal wallet adoption, and Wero pan-European expansion.
Product
Europe & Americas Local Payment
Accept iDEAL | Wero, SEPA, Bancontact, eps, BLIK, Przelewy24, and Multibanco across Europe through one unified API integration.

Need help mapping your payment stack?
Talk to HaiPay about acquiring, orchestration, local methods, and payout workflows.
Contact us