
Direct Answer
To accept online payments from French customers with high conversion, international merchants should combine Cartes Bancaires (CB) co-badged Visa and Mastercard acquiring, digital wallets (PayPal, Apple Pay, and Google Pay), and SEPA bank rails (SCT Inst and SDD). According to Banque de France Bulletin No. 256 (April 2025, ECB SPACE 2024 survey), online payments account for 25% of all French transactions, led by cards at 53% and digital wallets at 27% (including PayPal at nearly 18%), while Groupement CB processed 14.5 billion transactions across 78 million cards in 2025 (>95% co-badged). Qualified non-French entities can onboard via cross-border KYB without incorporating a local SAS or SARL, honor EU IFR Article 8(6) co-badged brand choice and October 2025 Verification of Payee rules, and settle natively in EUR.
Choosing a payment gateway for France takes more than a basic card form. French e-commerce runs on co-badged Cartes Bancaires (CB) cards, digital wallets, and SEPA bank rails. International merchants that ignore local French routing rules face false declines and avoidable FX spreads.
Banque de France Bulletin No. 256 (April 2025, ECB SPACE 2024 survey) shows online payments represent 25% of French transactions (vs. 21% euro area average). Cards capture 53% of online volume, while wallets rose 6 percentage points in two years to 27% (PayPal holds nearly 18%). Groupement CB recorded 78 million CB cards and 14.5 billion transactions in 2025.
How French Customers Pay Online: Banque de France Data, Cartes Bancaires (CB), Wallets, and SEPA
France is Europe's second-largest economy, yet its checkout mix differs sharply from Germany's invoice-and-wallet model. In Banque de France's 2024 SPACE survey, cards overtook cash at POS terminals for the first time as cash dropped to 43%. In September 2026, the OSMP reported French cashless volume grew 5.5% in 2025 (4.2% in value).
Online, cards and digital wallets drive 80% of French checkout volume, while SEPA credit transfer and direct debit rails power subscriptions and B2B invoices. Mobile wallets reached 19% of proximity card payments in 2025. SEPA Instant (SCT Inst) value doubled between 2024 and 2025 to reach 17% of credit transfers.
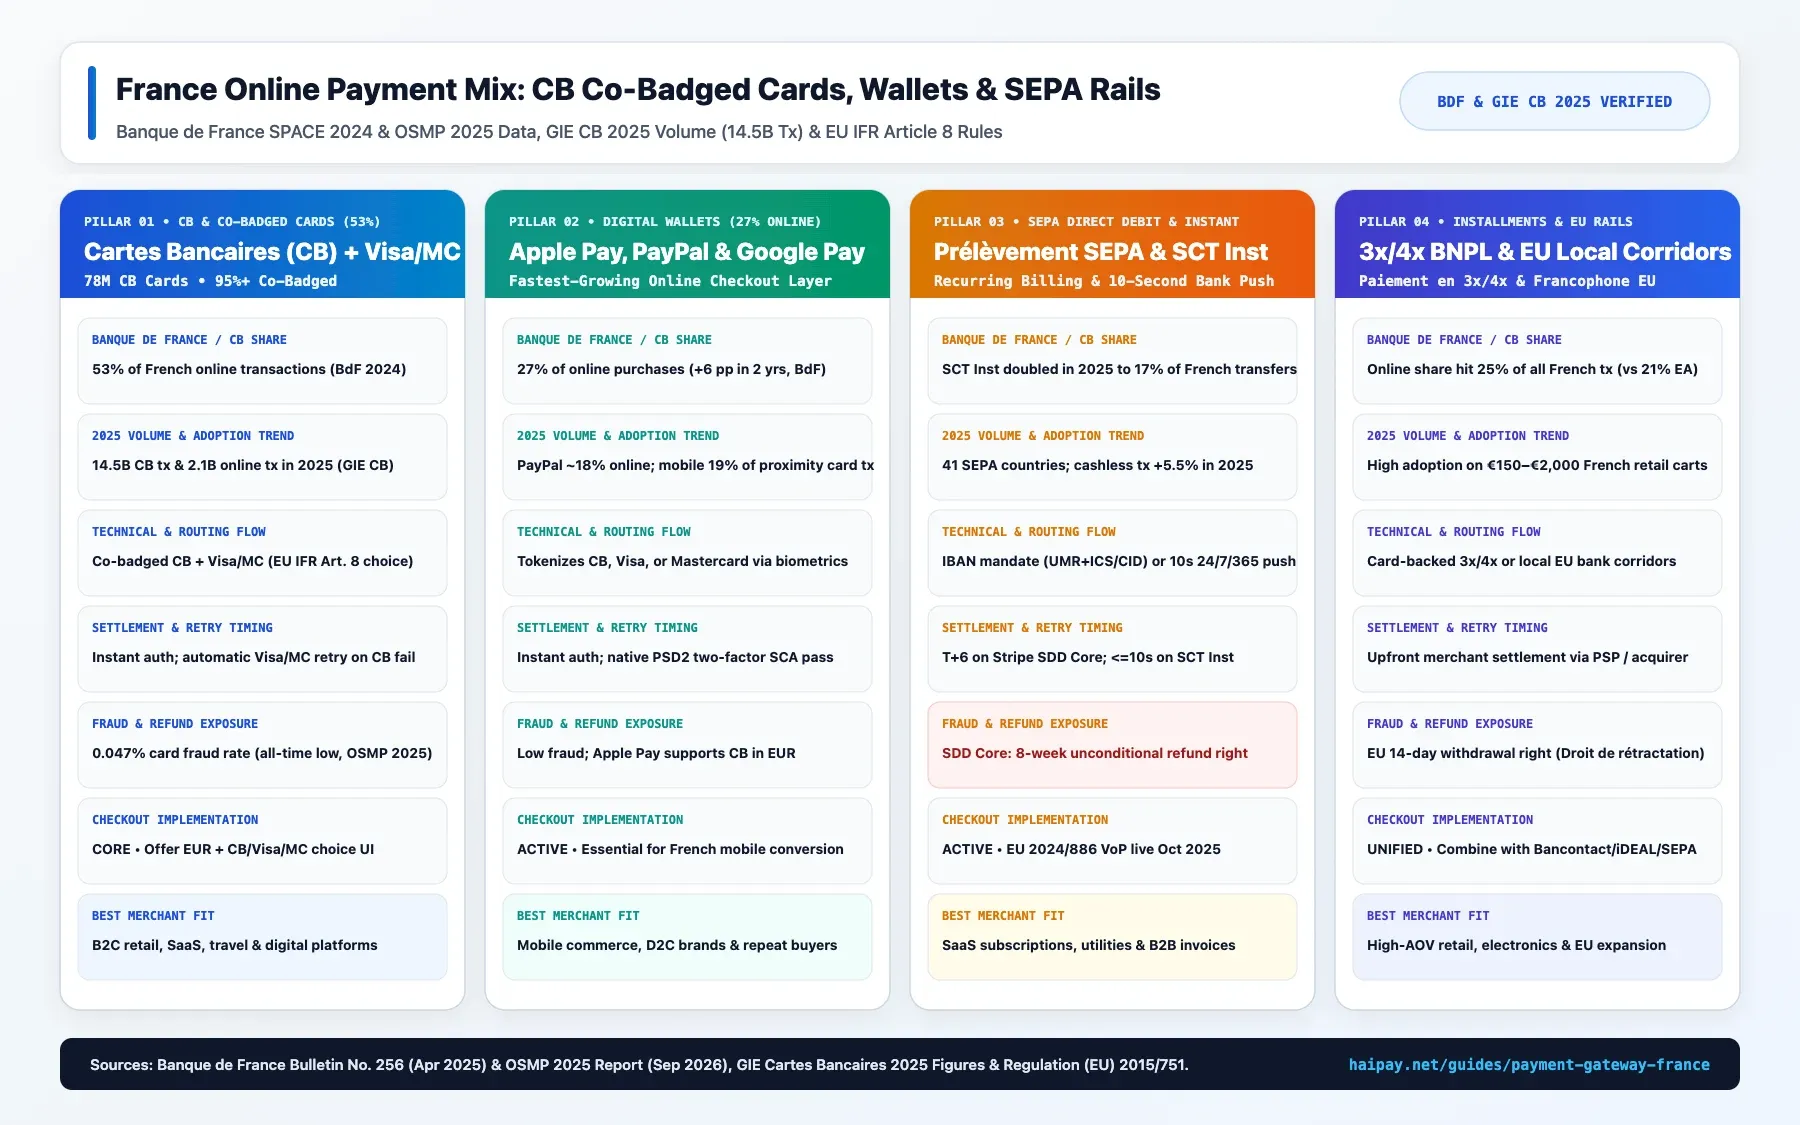
French Payment Rail | Verified Share & Scale | Settlement & Flow | Integration Action |
|---|---|---|---|
Cartes Bancaires (CB) Cards | 53% online share (BdF 2024); 78M cards, 14.5B txns, 2.1B online (2025). | >95% co-badged with Visa/Mastercard; immediate or deferred debit. | Support CB + Visa/Mastercard retry and IFR Art. 8(6) brand selector. |
PayPal, Apple Pay & Google Pay | 27% online wallet share (+6 pts); PayPal ~18%; mobile wallets 19% POS. | Instant tokenized auth; Apple Pay supports CB in EUR on Stripe. | Enable Apple Pay, Google Pay, and PayPal on mobile checkouts. |
SEPA Direct Debit (SDD) | 23.5B SEPA debits (9.6T EUR) in 2024; 11.3B eurozone debits H1 2025. | SDD Core settles T+6 on Stripe (10k EUR cap); 8-week recall window. | Use SDD Core for SaaS renewals; require SDD B2B for wholesale. |
SEPA Instant (SCT Inst) & Wero | SCT Inst value doubled in 2025 to 17% of credit transfers (OSMP). | <=10s settlement 24/7/365; €100k EPC cap; EPI Wero live. | Offer SCT Inst with Oct 2025 VoP alignment for B2B orders. |
Split Pay (Paiement en 3x/4x) | Used in French retail for €150–€2,000 baskets (Klarna, Alma, PayPal 4x). | Buyer pays in 3 or 4 parts; PSP settles merchant upfront. | Weigh 4.99% + €0.40 Klarna FR fees against card and SEPA costs. |
How Cartes Bancaires (CB) Co-Badging and EU IFR Article 8(6) Routing Work
Founded in 1984, Groupement des Cartes Bancaires (CB) settles over 65% of everyday French household consumption. In 2025, CB recorded 78 million cards, 14.5 billion transactions, 8 billion contactless payments, and 2.1 billion online transactions (after 76 million cards and €685 billion across 15 billion transactions in 2022).
Over 95% of CB cards are co-badged with Visa or Mastercard, including deferred debit cards (cartes à débit différé). Under Article 8(6) of EU Interchange Fee Regulation (EU) 2015/751, merchants may set a default network priority at checkout. French cardholders must be able to override that default when both brands are accepted in EUR.
Co-badged routing improves authorization rates and lowers dispute costs. On Stripe, if a CB authorization hits a technical decline, the gateway retries via Visa or Mastercard. Apple Pay also supports CB in EUR, and Stripe charges a 0 EUR dispute fee on uncontestable CB network disputes.
Digital Wallets, Paiement en 3x/4x, and Wero's Rollout in France
Banque de France data shows French shoppers increasingly pair cards with digital wallets. Online payment solutions rose 6 percentage points in two years to 27% of online transactions, with PayPal near 18%. Enabling Apple Pay and Google Pay alongside CB cards removes manual 16-digit card entry on mobile.
For €150 to €2,000 baskets, French buyers often use split installments (paiement en 3x ou 4x). Major French banks also launched the EPI Wero wallet in late 2024 to replace Paylib. Because Klarna on Stripe France starts at 4.99% + €0.40, co-badged cards and SEPA remain more economical for recurring flows.
Source: Banque de France Bulletin No. 256 (18 Apr 2025), OSMP Report (9 Sep 2026), Groupement CB 2025, and EUR-Lex Regulation (EU) 2015/751.
Can an Overseas Company Accept Payments from France Without a Local SAS or SARL?
Many cross-border SaaS, e-commerce, and digital teams assume selling into France requires incorporating a local SAS or SARL. In practice, qualified companies in the US, UK, Hong Kong, Singapore, or another EEA state can collect EUR from France without a French subsidiary.
In France, payment and e-money institutions are supervised by the ACPR (backed by the Banque de France) under the Code monétaire et financier and PSD2. Overseas merchants do not need their own ACPR license when using a compliant gateway; instead, they pass KYB underwriting and follow French checkout rules.
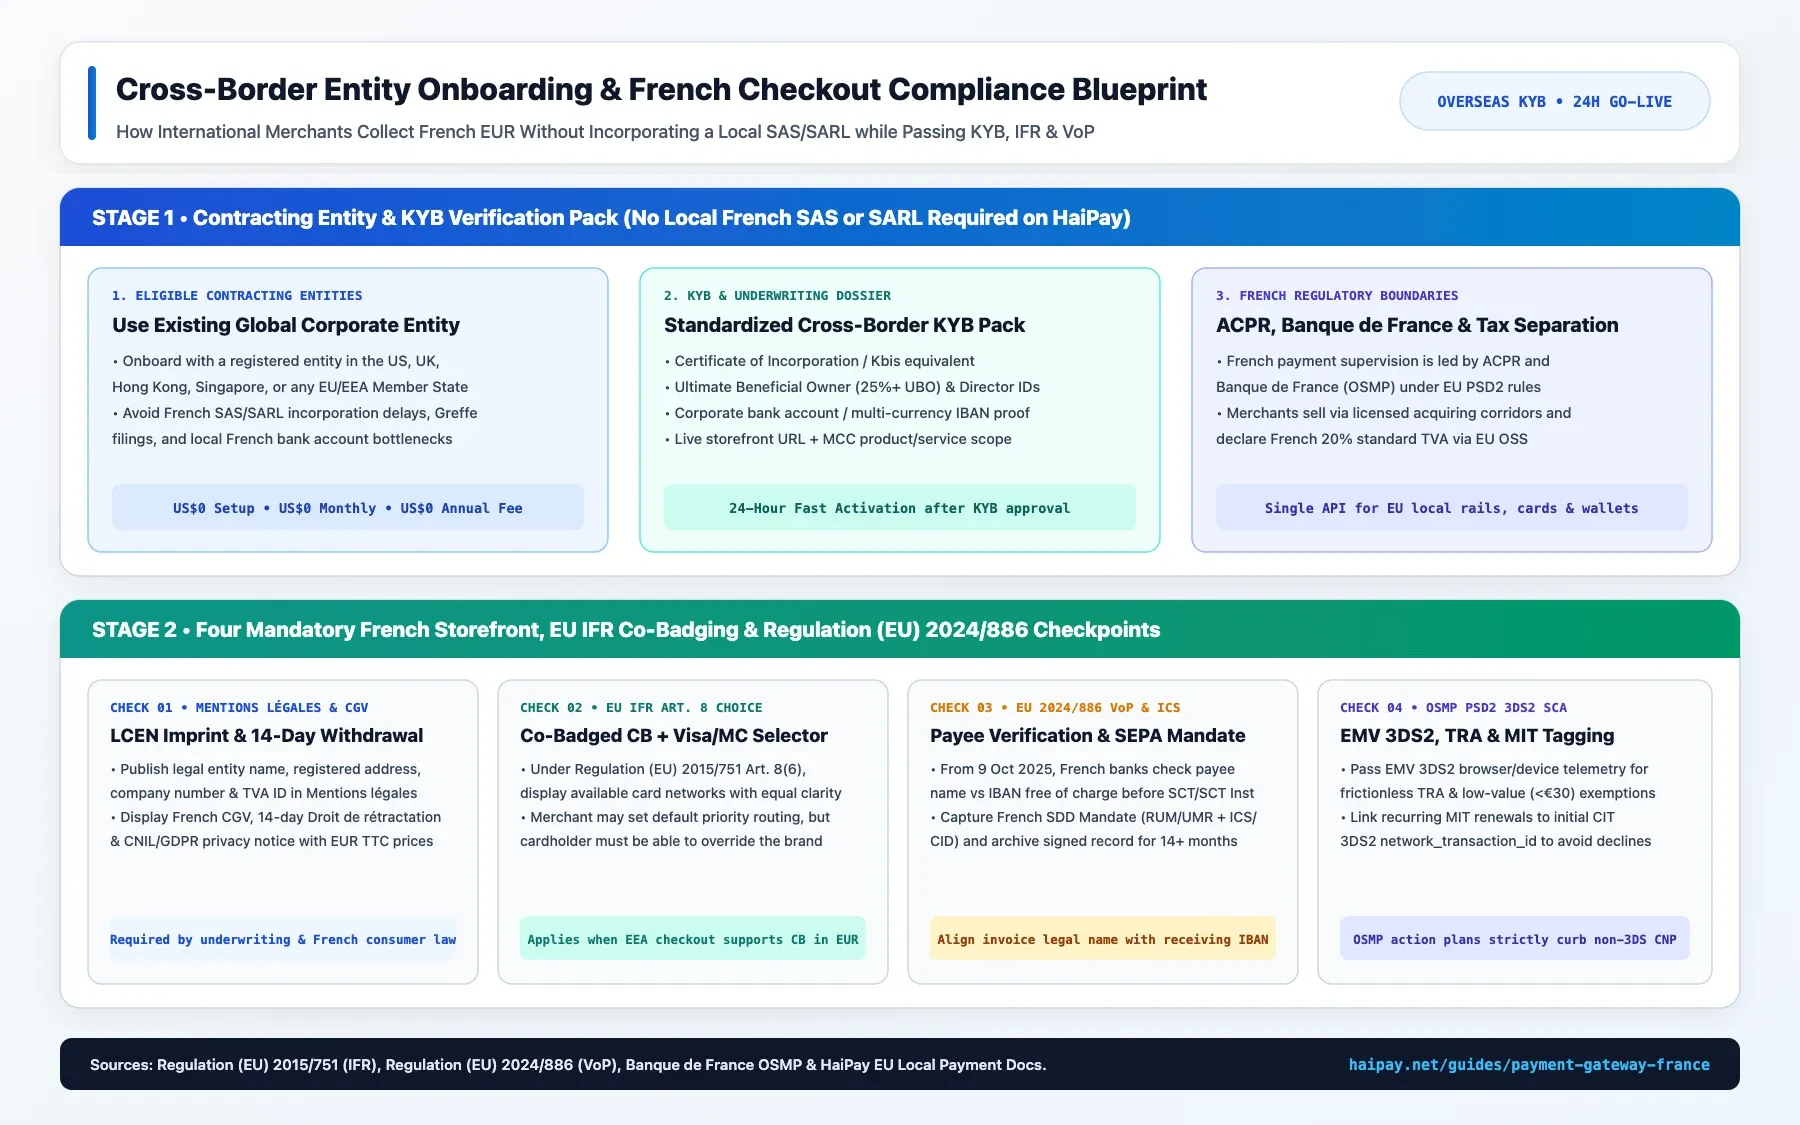
- Corporate KYB & UBO Dossier: Submit your Certificate of Incorporation, registry extract, 25%+ UBO and director IDs, and corporate bank proof.
- French Mentions Légales, CGV & 14-Day Withdrawal: Publish Mentions légales and CGV with your entity name, address, VAT/IOSS ID, RGPD notice, and 14-day droit de rétractation.
- IFR Article 8(6) Co-Badged Brand Choice UI: Show a brand selector after BIN detection on EEA EUR checkouts so cardholders can keep or override your CB / Visa / Mastercard default.
- Regulation (EU) 2024/886 Verification of Payee (VoP): Since 9 October 2025, eurozone banks verify the beneficiary name against the IBAN free of charge before transfer authorization (Article 5c; EMIs follow in 2027). Print your exact legal entity name on invoices to avoid No-Match warnings.
Source: Directive (EU) 2015/2366 (PSD2), Regulation (EU) 2015/751 (Art. 8), and Regulation (EU) 2024/886 (Arts. 5a–5d).
Managing French Payment Fraud, PSD2 3DS2 SCA, and SEPA Direct Debit Recall Risk
France operates one of Europe's strictest payment security regimes. In its 9 September 2026 report, the Banque de France OSMP recorded €1.241 billion in French payment fraud in 2025 (+3.8% in value), while volume fell 8% to 7.2 million transactions. Knowing how fraud and bank recalls work in France protects margins.
PSD2 Strong Customer Authentication (3DS2): Why French Card Fraud Hit 0.047%
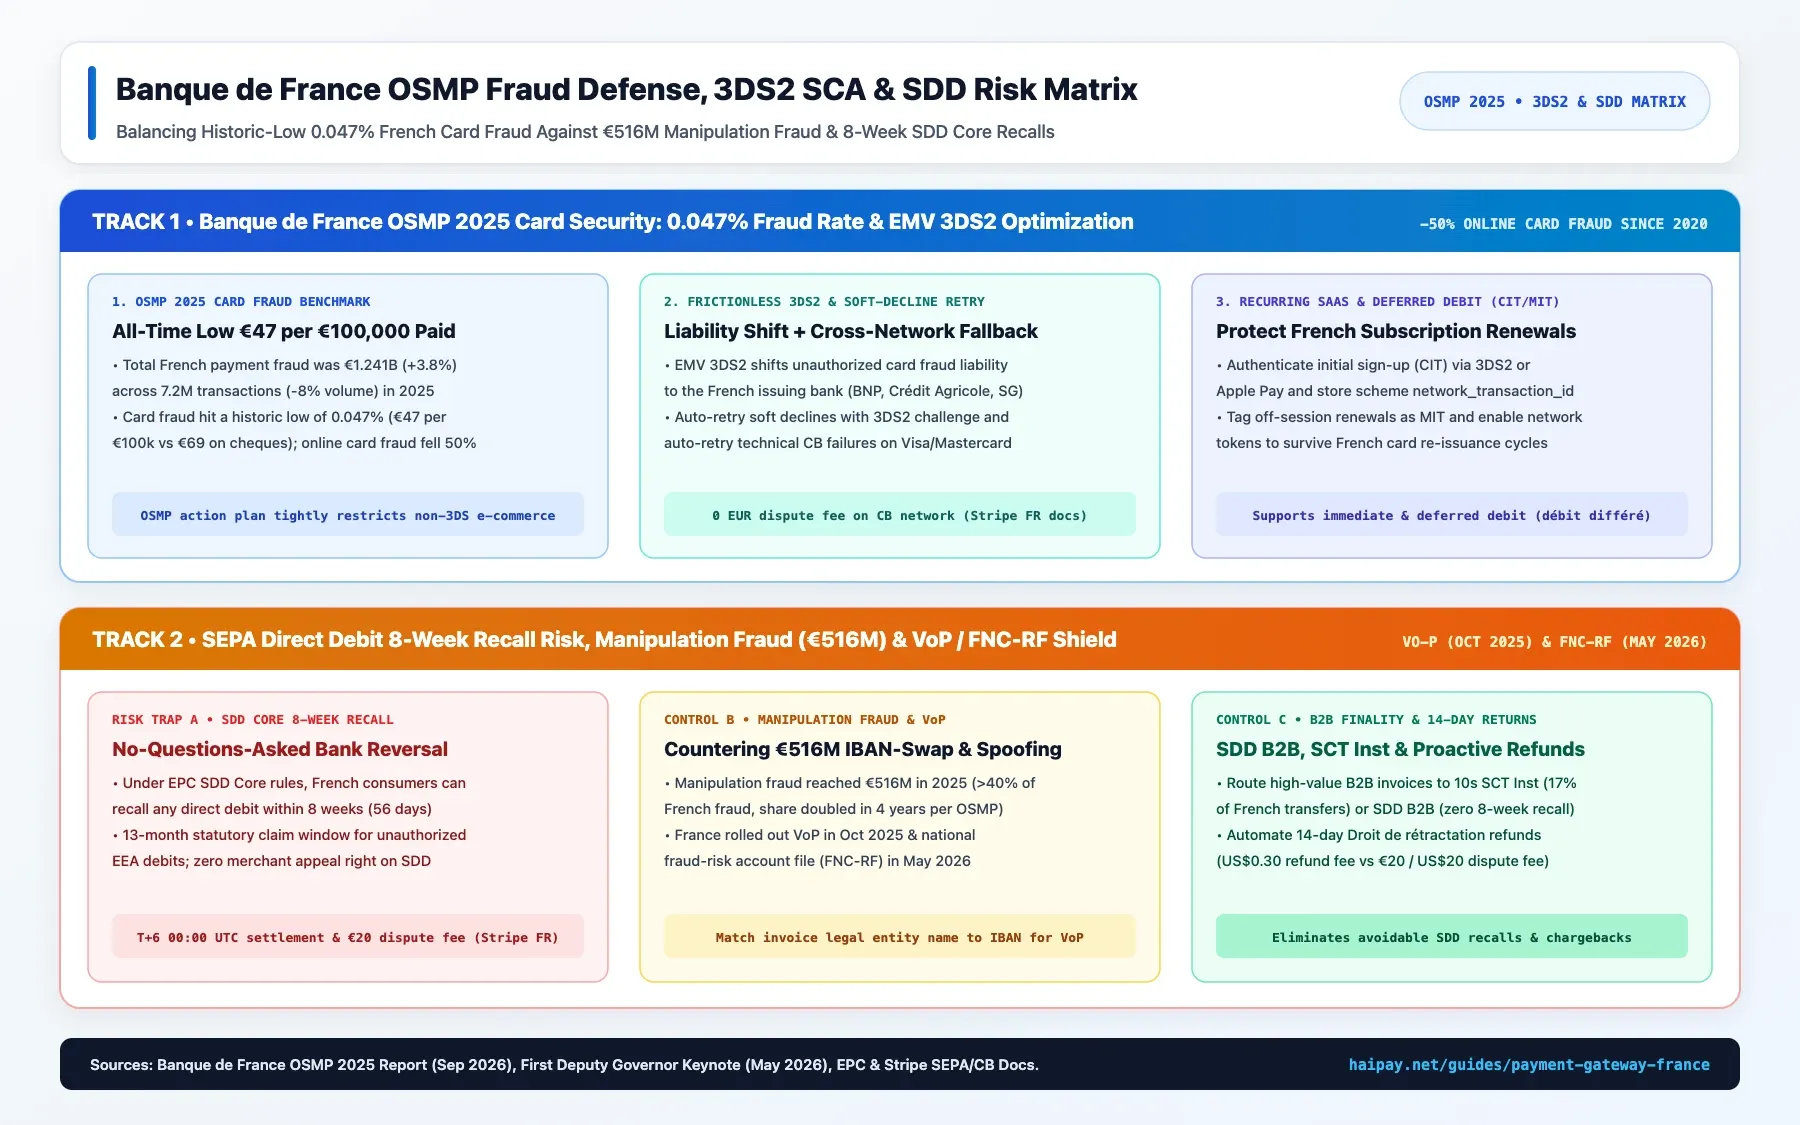
French issuers strictly enforce PSD2 Strong Customer Authentication via EMV 3-D Secure 2 (3DS2). Consequently, the Banque de France OSMP reported payment card fraud hit a record low of 0.047% in 2025 (€47 stolen per €100,000 paid, vs. €69 on cheques). Online card fraud in France fell 50% between 2018/2020 and 2025.
To preserve conversion while keeping liability shift, merchants should pass browser, device, and billing telemetry on 3DS2 requests. Low-risk orders qualify for frictionless Transaction Risk Analysis (TRA) or low-value (<€30) exemptions. For subscriptions, pass the initial Customer-Initiated Transaction (CIT) trace ID so off-session Merchant-Initiated Transactions (MIT) clear.
SEPA Direct Debit 8-Week Recalls vs. Manipulation Fraud (€516M) and FNC-RF
Under EPC SDD Core rules, merchants notify payers 14 calendar days before debiting (shortenable to 2 calendar days on Stripe). Single SDD debits on Stripe cap at 10,000 EUR and settle T+6 at 00:00 UTC. SDD Core grants French consumers an unconditional 8-week (56-day) refund right plus a 13-month unauthorized claim window.
Banks reverse 8-week SDD Core recalls automatically, and Stripe France charges €20.00 per dispute (vs. HaiPay's US$0.30 refund fee). For B2B invoices, require SEPA Instant (SCT Inst) or SDD B2B, which waives the 8-week recall right. Meanwhile, manipulation fraud (spoofed bank calls and IBAN swaps) hit €516 million in 2025 (>40% of French fraud), addressed by October 2025 VoP checks and the May 2026 FNC-RF registry.
Risk Dimension | CB / Visa / Mastercard (3DS2) | SDD Core (Prélèvement SEPA) | SDD B2B & SCT Inst (VoP) |
|---|---|---|---|
Settlement | Instant auth; cross-border settlement as fast as T+5. | T+6 at 00:00 UTC on Stripe (1–2d debit + 5d refusal). | SCT Inst: <=10s 24/7/365; SDD B2B: 1–3 business days. |
Recall Window | 0.047% card fraud rate (OSMP 2025); 120d chargeback. | 8-week unconditional recall + 13m unauthorized claim. | Zero 8-week unconditional refund; irrevocable SCT Inst. |
Dispute Rule | 3DS2 shifts fraud liability; CB disputes €0 on Stripe. | No appeal in first 8 weeks; €20 Stripe FR dispute fee. | Oct 2025 VoP IBAN check + May 2026 FNC-RF screening. |
French Use Case | E-commerce retail, apps, and CIT+MIT SaaS renewals. | Recurring consumer memberships and utilities. | High-value B2B wholesale and instant stock release. |
Source: Banque de France OSMP Report (9 Sep 2026), Denis Beau speech (26 May 2026), and Stripe SEPA & CB docs.
Payment Gateway France Fee Comparison: Domestic Rates, Cross-Border Markups, and EUR Treasury
Benchmarking a French payment gateway requires reviewing cross-border surcharges, BNPL fees, and settlement FX costs. On Stripe France's domestic schedule, standard EEA cards cost 1.5% + €0.25 and premium/commercial EEA cards cost 2.8% + €0.25. UK cards cost 2.5% + €0.25 (plus 2% FX if conversion applies), and cards outside Europe cost 3.15% + €0.25 (plus 2% FX).
For bank and BNPL rails on Stripe France, SEPA Direct Debit costs €0.35 per transaction (10,000 EUR limit, SDD Core only). US cross-border Stripe accounts pay 0.8% + $0.30 (capped at $6.00) plus FX fees for SDD. Klarna on Stripe France starts at 4.99% + €0.40, disputes cost €20.00, and alternative currency payouts cost 1%.
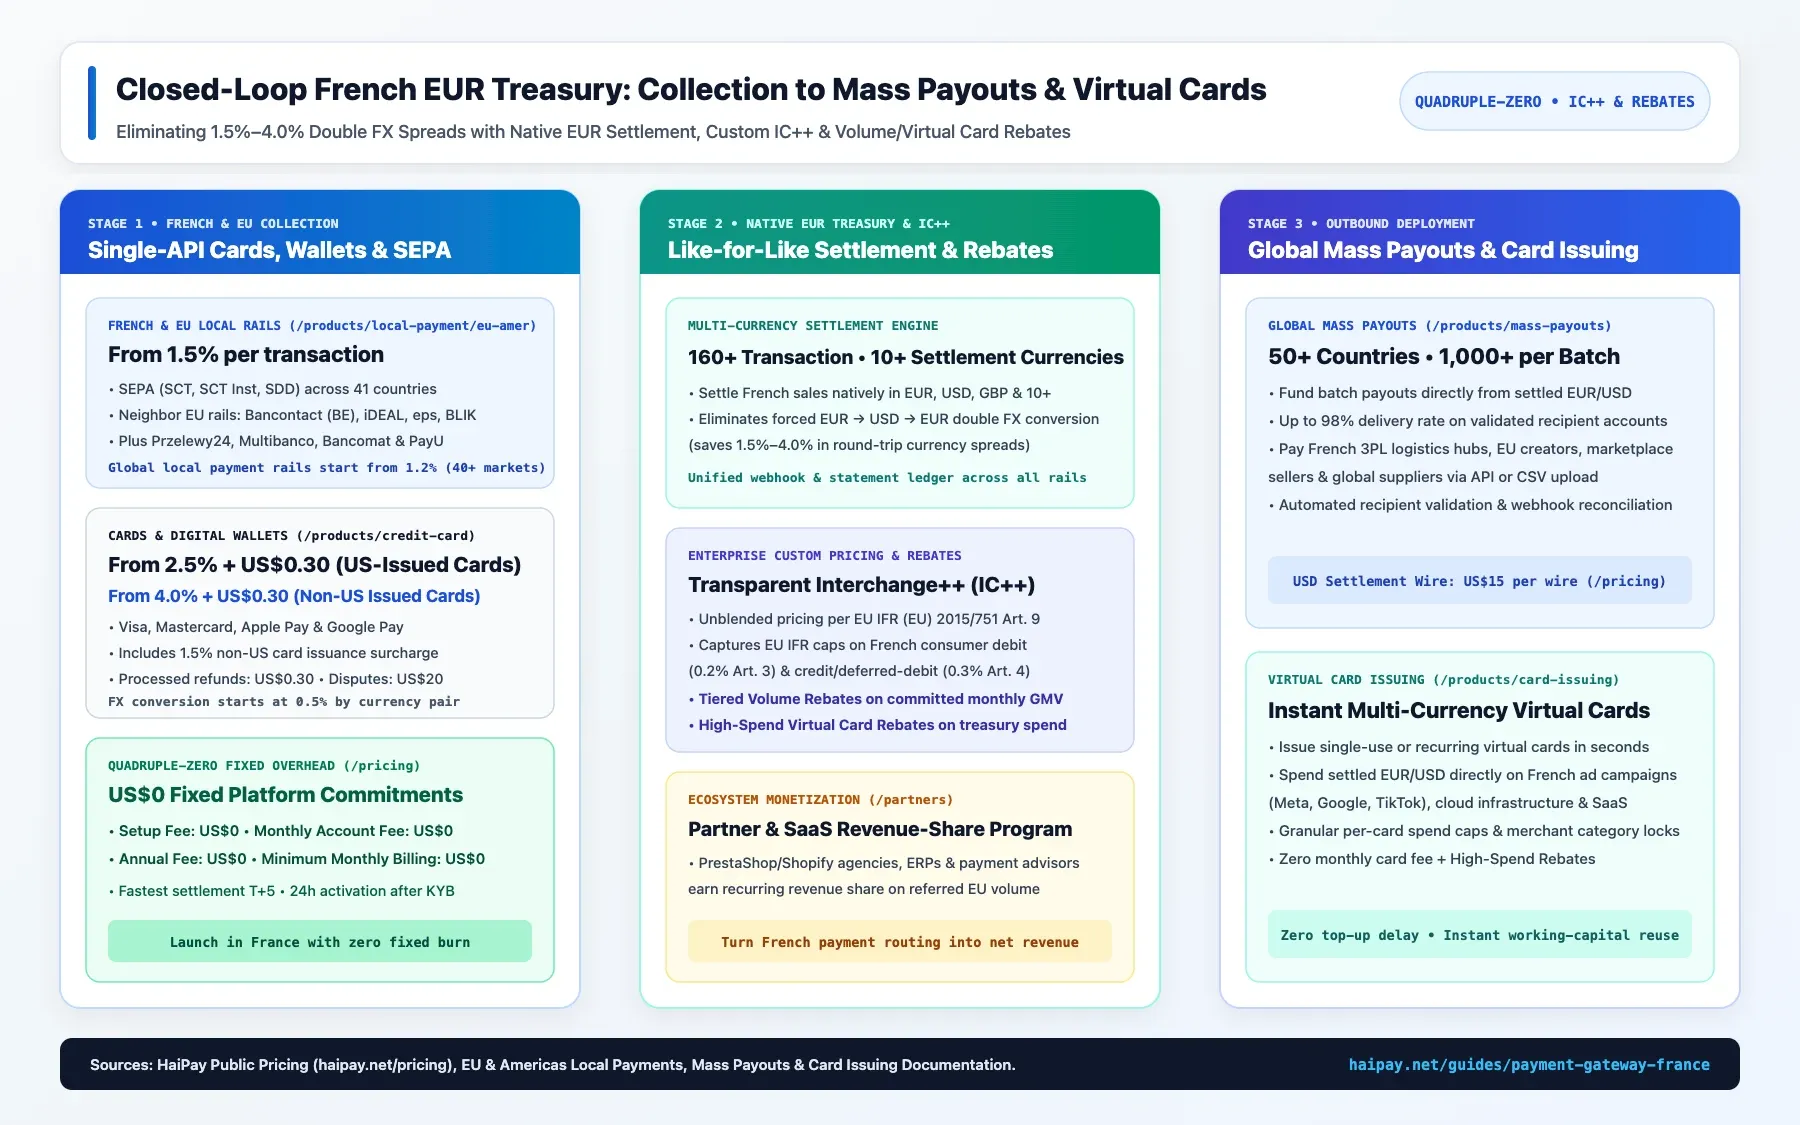
International merchants serving French buyers without a local SAS or SARL can unify card and bank rails through HaiPay's Europe and Americas local payment infrastructure. One API pairs SEPA collection with online credit and debit card acquiring built around French checkout execution:
- Co-Badged Cartes Bancaires (CB), Visa & Mastercard Routing. Process French CB co-badged Visa and Mastercard cards alongside Apple Pay and Google Pay from 2.5% + US$0.30 for US cards via a US entity. Non-US cards start from 4.0% + US$0.30 (including a 1.5% non-US surcharge, FX from 0.5%, US$0.30 refunds, and US$20 disputes).
- Unified SEPA & European Local Rails (From 1.5%). Accept SEPA alongside iDEAL, Bancontact, eps, BLIK, Przelewy24, and Multibanco starting from 1.5% (global regional rails from 1.2% across 40+ markets).
- PSD2 3DS2 Frictionless Auth & Direct Overseas KYB. Pass device telemetry to maximize EMV 3DS2 Transaction Risk Analysis (TRA) exemptions and onboard qualified US, UK, HK, SG, and EEA entities without a French SAS/SARL. Accounts carry US$0 setup, US$0 monthly, US$0 annual, and US$0 minimum monthly billing fees.
- EEA Consumer Interchange Pass-Through (IC++). High-volume merchants can request unblended Interchange++ (IC++) pricing under EU IFR Regulation (EU) 2015/751, capturing statutory 0.20% debit and 0.30% credit interchange caps.
Eliminating double FX conversion on French EUR revenue saves 1.5% to 4.0% in margin. When a processor forces EUR sales into USD at settlement and you later convert USD back into EUR to pay French 3PL warehouses, suppliers, or creators, you lose two FX spreads.
With HaiPay, merchants collect in 160+ currencies and settle natively in EUR, USD, GBP, and 10+ currencies on a T+5 card cycle. Supported local rails settle as fast as T+1, preserving French checkout margin in native EUR. Settled EUR funds route directly into Global Mass Payouts across 50+ countries (1,000+ recipients per batch with up to 98% delivery on validated accounts, or US$15 per USD wire).
Dimension | Stripe France (FR) | Stripe US Cross-Border | HaiPay Cross-Border & EU |
|---|---|---|---|
Entity Rule | Local French / EEA entity required. | US entity accepted; cross-border fees apply. | Qualified US, UK, HK, SG, or EEA entity via KYB (no SAS/SARL). |
SEPA & Local Rails | €0.35 SDD Core (10k EUR cap); Klarna from 4.99% + €0.40. | 0.8% + $0.30 ($6.00 cap) + intl & FX fees. | From 1.5% across SEPA, iDEAL, Bancontact, eps, BLIK, P24 & Multibanco on published pricing (global from 1.2%). |
Cards & Wallets | 1.5% + €0.25 (EEA), 2.8% + €0.25 (premium), 2.5% + €0.25 (UK), 3.15% + €0.25 (intl) + 2% FX. | US rate + 1.5% intl card + 1% FX. | From 2.5% + US$0.30 (US cards); From 4.0% + US$0.30 (non-US); FX from 0.5%. |
Fixed Overhead | €0 pay-as-you-go fixed fees. | $0 pay-as-you-go fixed fees. | US$0 setup, US$0 monthly, US$0 annual & US$0 min. monthly. |
EUR Treasury | Local EUR payouts; 1% alt-currency fee. | Forced USD unless multi-currency account. | Native EUR T+5 settlement; EUR routing to 50+ country mass payouts. |
Source: Stripe France pricing (stripe.com/en-fr/pricing), Stripe CB & SEPA docs, and HaiPay Pricing (haipay.net/pricing), verified Nov 2026.
Downloadable France Payment Gateway Launch & EUR Reconciliation Checklist (CSV)
Launching in France requires Mentions légales disclosures, IFR Article 8(6) brand choice, October 2025 VoP invoice alignment, and EUR ledger reconciliation. Compare local vs. cross-border acquiring, review cross-border acquiring fees and payment gateway reconciliation, and download the France Payment Gateway Launch & EUR Reconciliation Checklist (CSV).
Need to configure Cartes Bancaires co-badged card routing, PSD2 3DS2 frictionless exemptions, and SEPA collection for French buyers without incorporating a local SAS or SARL? Contact HaiPay's payment architects to review your corporate KYB dossier and activate native T+5 EUR settlement for your French storefront.
Sources
- Banque de France — Bulletin No. 256: Cash vs. Digital Payments (18 Apr 2025) — Accessed 8 Nov 2026.
- Banque de France OSMP — Payment Fraud in 2025 (9 Sep 2026) — Accessed 8 Nov 2026.
- Banque de France — Denis Beau Keynote on Payment Security (26 May 2026) — Accessed 8 Nov 2026.
- Groupement des Cartes Bancaires (CB) — Key Figures (2025) — Accessed 8 Nov 2026.
- Stripe Docs — Cartes Bancaires (CB) & Co-Badged Compliance — Accessed 8 Nov 2026.
- EUR-Lex — Regulation (EU) 2015/751 on Card Interchange Fees — Published 29 Apr 2015; accessed 8 Nov 2026.
- EUR-Lex — Regulation (EU) 2024/886 on Instant Credit Transfers — Published 19 Mar 2024; accessed 8 Nov 2026.
- European Central Bank (ECB) — SEPA Overview (22 May 2025) — Accessed 8 Nov 2026.
- Stripe France — Pricing Schedule & SEPA Direct Debit Docs — Accessed 8 Nov 2026.
- HaiPay — Pricing, Europe & Americas Local Payments & Mass Payouts — Accessed 8 Nov 2026.
FAQ
According to Banque de France Bulletin No. 256 (published 18 April 2025 based on the ECB SPACE 2024 survey), online payments represent 25% of all French payment transactions (above the 21% euro area average). Payment cards lead French e-commerce at 53% of online transactions—anchored by France's national Cartes Bancaires (CB) scheme (78 million cards and 2.1 billion remote transactions in 2025)—while online payment solutions and wallets grew 6 percentage points in two years to reach 27% (including PayPal at nearly 18%), complemented by SEPA Direct Debit, SEPA Instant (17% of credit transfers in 2025), and 3x/4x split installments.
Founded in 1984, Groupement des Cartes Bancaires (CB) is France's domestic interbank card network, accounting for over 65% of everyday French household consumption with 78 million cards and 14.5 billion transactions in 2025. Over 95% of CB cards are co-badged with Visa or Mastercard. Under Article 8(6) of EU Regulation (EU) 2015/751, merchants can configure an automatic default network priority at checkout provided cardholders can override that choice when both brands are accepted in EUR, while gateways like Stripe automatically retry CB technical declines over Visa or Mastercard.
Yes. Qualified cross-border businesses incorporated in the United States, the United Kingdom, Hong Kong, Singapore, or another EEA Member State do not need to incorporate a French SAS or SARL to collect EUR from French buyers. Through HaiPay's single API, overseas entities complete standard KYB verification and activate SEPA and European local rails (from 1.5%) alongside card and wallet acquiring (from 2.5% + US$0.30 for US cards via a US entity, or from 4.0% + US$0.30 for non-US cards) with US$0 setup, monthly, annual, and minimum monthly billing fees.
Articles 3 and 4 of Regulation (EU) 2015/751 cap multilateral interchange fees on EEA consumer debit cards at 0.2% and EEA consumer credit cards at 0.3% per transaction (while Article 9 requires acquirers to disclose unblended merchant service charges upon request). Rather than paying flat blended tiers on every transaction, high-volume merchants can request unblended Interchange++ (IC++) pricing under Article 9 to capture lower EEA consumer debit and credit interchange costs on French checkouts.
According to the Banque de France OSMP 2025 report (published 9 September 2026), French payment card fraud reached an all-time low of 0.047% in 2025 (€47 per €100,000 paid), and online card fraud dropped 50% between 2018/2020 and 2025 due to PSD2 Strong Customer Authentication (EMV 3DS2). Merchants should send full browser and device telemetry to trigger frictionless Transaction Risk Analysis (TRA) exemptions on low-risk orders, authenticate initial Customer-Initiated Transactions (CIT) via 3DS2 or Apple Pay/Google Pay biometrics, and pass network transaction IDs on recurring Merchant-Initiated Transactions (MIT).
Under EPC SDD Core (Prélèvement SEPA) rules, French consumers can trigger a no-questions-asked unconditional refund for 8 weeks (56 days) after a debit and claim unauthorized debits for 13 months. For high-ticket corporate sales, merchants should use SDD B2B (which waives the 8-week unconditional refund right) or 10-second SEPA Instant (SCT Inst). In addition, since 9 October 2025 under Regulation (EU) 2024/886 Article 5c, eurozone banks run free Verification of Payee (VoP) matching beneficiary names against IBANs before transfer authorization—complemented in France by the May 2026 FNC-RF fraud-risk account registry.
Double FX conversion happens when a gateway forces French EUR checkout proceeds into USD at settlement and the merchant later converts USD back into EUR to pay French 3PL warehouses or European suppliers, losing 1.5% to 4.0% in currency spreads. With HaiPay, merchants collect in 160+ transaction currencies, settle natively in EUR, USD, GBP, and 10+ currencies, and deploy settled EUR directly into Global Mass Payouts across 50+ countries without forced currency conversion.

Related HaiPay surfaces
Explore the payment stack
Guide
SEPA Payments Guide: SCT, Instant & Direct Debit
Deep dive into SCT, 10-second SCT Inst, SDD Core 8-week refund rules, SDD B2B finality, and Regulation (EU) 2024/886 VoP across 41 countries.
Guide
Payment Gateway Germany: SEPA, Cards & Local Rails
Compare France's card-and-wallet checkout mix against Germany's EHI 2025 invoice, PayPal, and SEPA Direct Debit landscape.
Product
Europe & Americas Local Payment
Accept SEPA, iDEAL, Bancontact, eps, BLIK, Przelewy24, and Multibanco across Europe through one unified API integration.
Product
Credit & Debit Card Acquiring
Process Visa, Mastercard, Apple Pay, and Google Pay in France with custom IC++ pricing and volume rebates.

Need help mapping your payment stack?
Talk to HaiPay about acquiring, orchestration, local methods, and payout workflows.
Contact us