


Direct Answer
Alternative payment methods (APMs) are ways to pay outside the standard credit- or debit-card flow: digital wallets, Pay by Bank and other account-to-account payments, bank transfers and direct debit, buy now pay later, local card schemes, QR payments, voucher or cash-reference payments, real-time payment networks, and cryptocurrency or stablecoin payments where legally available. The category is a merchant-planning umbrella rather than a regulated classification, so the right mix depends on the market, the customer segment, and how settlement, refunds, disputes, and reconciliation work for each method. Start from the markets you serve, confirm provider availability and operating rules, then add the methods that measurably improve checkout completion.
Alternative payment methods are payment options outside the traditional card payment flow. They can include digital wallets, Pay by Bank and other account-to-account payments, bank transfers, buy now pay later, local card schemes, QR payments, vouchers, real-time payment networks, cryptocurrency and stablecoin payments where legally available and other market-specific ways customers prefer to pay.
For businesses selling across markets, APMs shape checkout trust, payment completion, operational complexity, and the way finance teams handle settlement, refunds, reconciliation, and payment risk.
For a merchant, the practical question is simple: which payment methods should appear at checkout, in which markets, for which customers, and with what operational tradeoffs?
Use this guide to build that decision. When you are ready to validate availability for your own checkout, review HaiPay Checkout or talk to the payments team to confirm availability, settlement, refunds, and implementation requirements before launch.
What are alternative payment methods?
Alternative payment methods, often shortened to APMs, are ways to pay that are not the standard credit-card or debit-card payment flow. The exact boundary varies by provider and market, but most APM guides include wallets, bank-based payments, direct debit, buy now pay later, cash or voucher flows, QR payments, local card schemes, and other local payment options. The category boundary is not globally standardized, so this guide uses APM as a merchant-planning umbrella rather than a regulatory classification. Each method should be verified against official scheme, regulator, or provider documentation for the target market.
Digital payment adoption is expanding across markets. The World Bank’s Global Findex 2025, based on nationally representative surveys of about 148,000 adults across 141 economies, found that 42% of adults in low- and middle-income economies made an in-store or online digital merchant payment in 2024, up from 35% in 2021. This is a digital-payment adoption measure rather than a direct estimate of APM market share, but it shows why merchants need market-specific payment-method planning.
That definition matters because "alternative" does not mean niche. In many markets, a local wallet, bank transfer flow, account-to-account option, or domestic payment scheme may feel more familiar to customers than an international card checkout. The right payment mix is therefore a market decision, not just a feature list.
For B2B and cross-border businesses, APM selection usually comes down to five questions:
- Does the customer already trust this method?
- Does the method fit the transaction size and purchase context?
- What does the payment flow ask the customer to do?
- How do settlement, refunds, failures, and disputes work?
- Can the business support the method operationally after launch?
Why alternative payment methods matter
Payment methods influence whether a customer recognizes the checkout, completes authentication, understands what will happen next, and feels comfortable paying. A card-only checkout can work well in some segments, but it can also create friction when customers expect a local wallet, bank transfer, QR code, or domestic payment network.
APMs matter most when a business is expanding across countries, selling to customers with strong local payment habits, supporting recurring or invoice-like flows, or trying to reduce friction in high-intent checkout sessions. They also matter when finance, operations, and support teams need clearer answers about reconciliation, refund timing, and failed-payment recovery.
The strongest APM strategy is not "add every method." It is "add the methods that match the buyer, market, and operating model." That is the difference between a useful checkout and a crowded one.
Main types of alternative payment methods
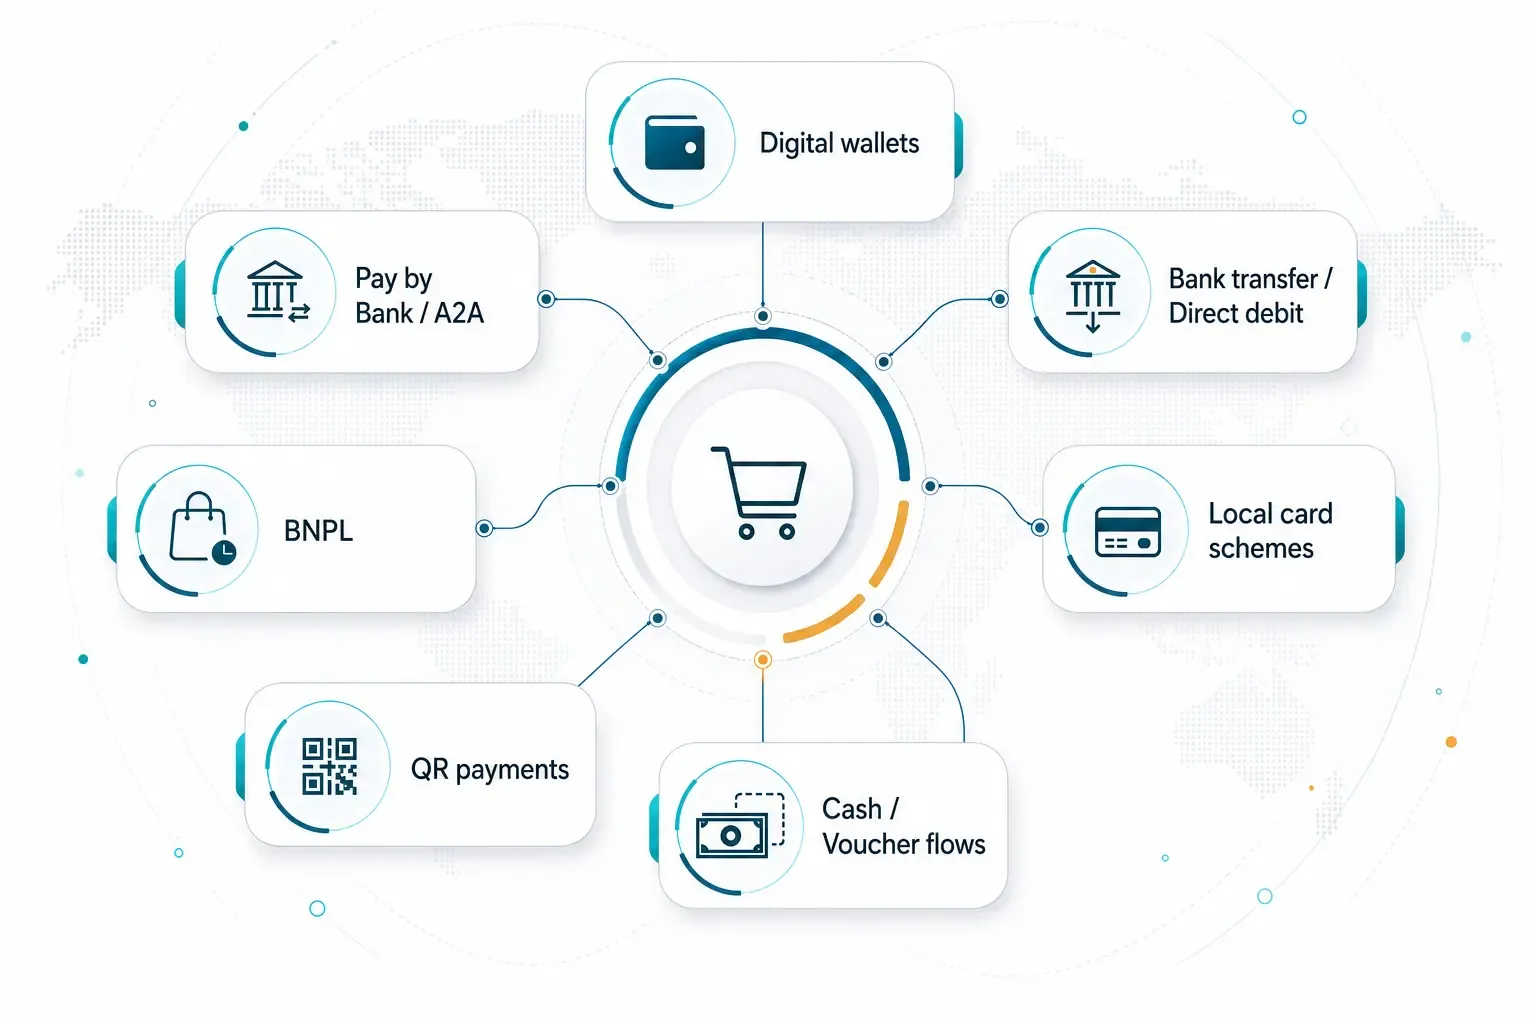
The table below groups common APM categories by the job they do at checkout. Availability, settlement timing, refund rules, and compliance requirements vary by country, provider, merchant category, and payment method, so every row should be confirmed before implementation.
APM type | What the customer does | Where it often fits | Key questions before launch |
|---|---|---|---|
Digital wallets | Selects a wallet and confirms payment through an app, browser, or wallet account | Consumer checkout, mobile checkout, repeat buyers, local wallet markets | Which wallets are trusted in the target market? How are refunds, failures, and disputes handled? |
Pay by Bank and account-to-account payments | Authorizes payment from a bank account, often through bank authentication or open-banking-style flows | Bank-trusted markets, lower-card-usage segments, account-funded checkout, invoice-like flows | Which rails are used? How does authentication work? Are refunds and settlement handled through the same flow? |
Bank transfers and direct debit | Pays from a bank account through transfer, debit authorization, or local bank-payment scheme | Larger-ticket purchases, recurring payments, B2B-style flows, markets with strong bank payment habits | What is the confirmation timing? How are failed or reversed payments handled? |
Buy now pay later | Selects an installment or deferred-payment provider | Retail, discretionary purchases, higher average order value categories | Who owns credit decisioning, customer communication, refunds, and merchant settlement? |
Local card schemes | Pays with a domestic or regional card brand | Markets where local card networks have strong acceptance and customer recognition | Is the local scheme relevant to the target market? Is acceptance supported by the acquiring setup? |
QR payments | Scans or displays a QR code and confirms payment in a banking or wallet app | Mobile-first markets, in-person-to-online bridges, local bank or wallet ecosystems | Is the QR flow static or dynamic? How is payment status confirmed? |
Cash, voucher, or convenience-store payments | Receives a code or reference and pays offline or through a local network | Cash-preference segments, underbanked users, local cash networks | How long is the payment window? How are unpaid orders expired and reconciled? |
Cryptocurrency and stablecoin payments | Pays from a digital-asset wallet; the provider may convert the payment to fiat or settle the asset directly | Selected cross-border or digital-native use cases where legally and operationally supported | Which assets and networks are supported? How are exchange rates, settlement, refunds, reversibility, AML/sanctions screening, accounting, and tax handled? |
Real-time payment networks | Initiates an account-to-account payment, often through a bank app, redirect, or QR flow | Markets built around instant domestic rails such as UPI or Pix | How is payment confirmation returned? How do refunds, returns, fraud controls, reconciliation, and failed or pending states work? |
Alternative payment methods vs card payments
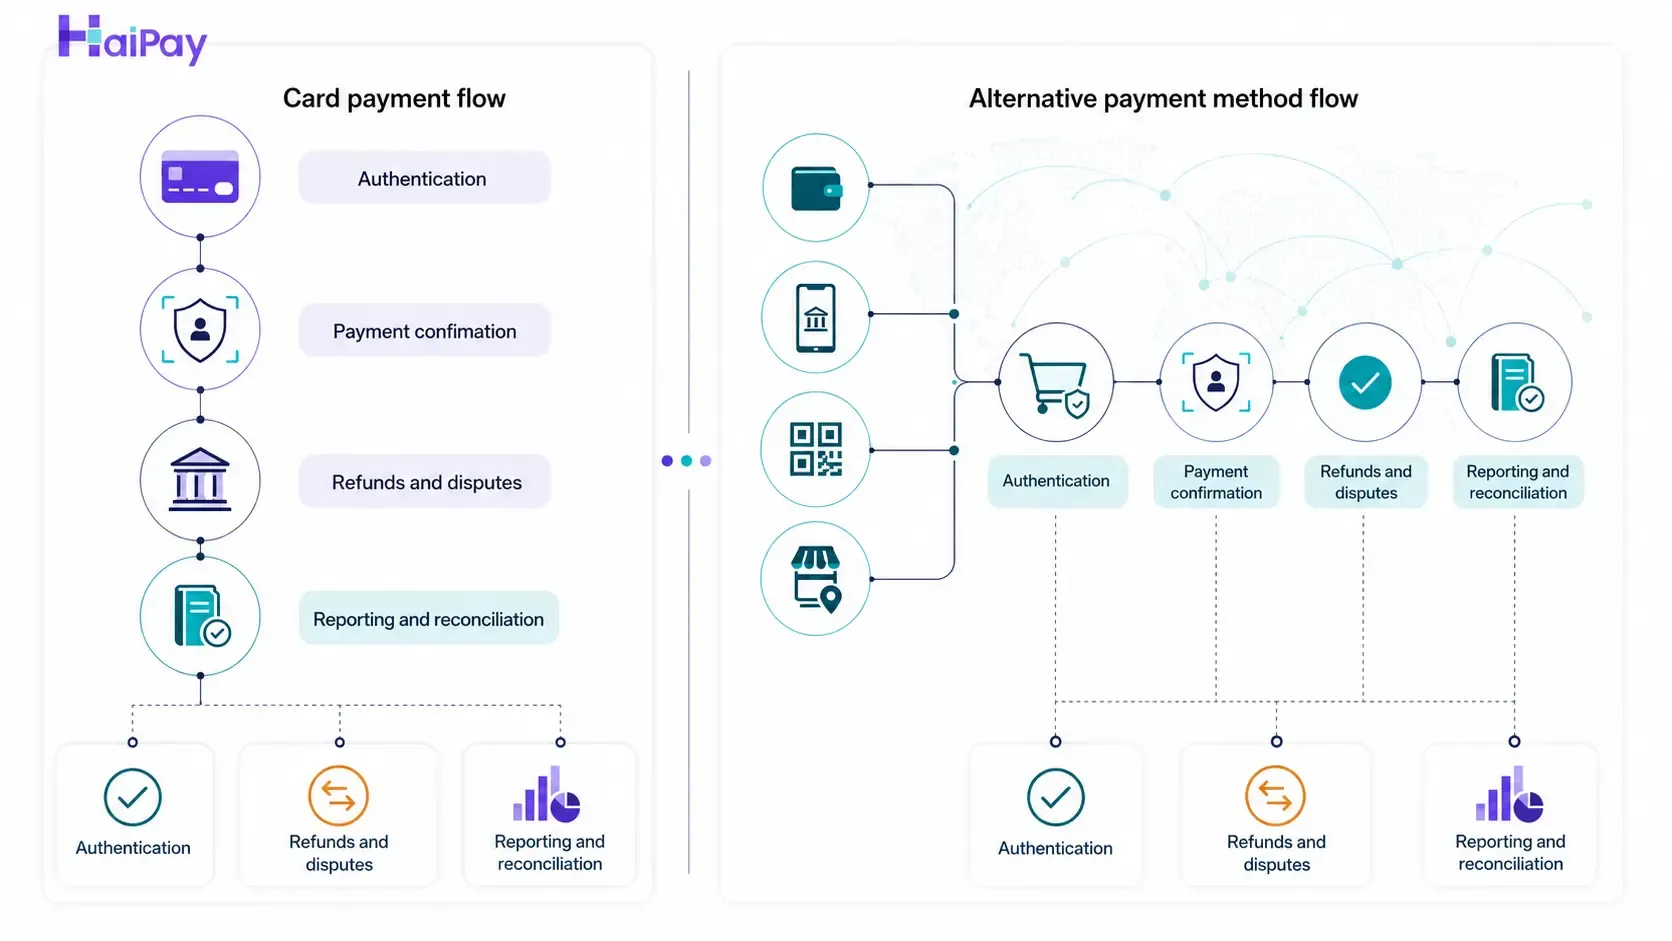
Cards are still a major part of online payment acceptance, but APMs differ from cards in how the customer authorizes payment, how the payment is confirmed, and how post-payment operations work.
Area | Card payments | Alternative payment methods |
|---|---|---|
Customer recognition | Familiar in many online markets | Often stronger when the method is local, bank-based, wallet-based, or already part of the customer's daily payment habits |
Authentication | Card details, wallet token, 3DS, or issuer authentication depending on setup | Varies by method: wallet login, bank authentication, QR scan, bank app confirmation, provider approval, voucher payment, or local scheme flow |
Payment confirmation | Usually immediate authorization response, with later clearing and settlement | Can be immediate, delayed, pending, expired, or manually reconciled depending on method |
Refund handling | Commonly card-network-driven, with established card refund patterns | Varies by method and provider. Refund route, timing, and customer communication must be verified |
Disputes and reversals | Card chargeback and dispute rules often apply | Rules differ widely. Some methods have disputes, some have reversals, and some require separate operational handling |
Implementation work | Card acquiring, tokenization, authentication, fraud rules, reporting | Method selection, market routing, local UX, status handling, reconciliation, support scripts, and provider-specific rules |
Are alternative payment methods more secure than card payments?
Neither side is categorically safer — they concentrate risk in different places.
Authentication. Many APMs authenticate inside the customer's own banking or wallet app, typically with biometrics or device binding, so there is no card number to steal or re-use. Cards compensate with 3-D Secure and network tokenization, but the credential model is still share-a-number-then-protect-it.
Revocability. Most card payments are pull payments with a built-in reversal path. Many APMs — especially real-time bank transfers — are push payments: the customer sends funds, and once settled they are final. That finality protects merchants from payment fraud on the rail itself, but it also means an error or scam is harder to unwind.
Dispute protection. Cards carry a formal chargeback framework with defined reason codes and merchant defense rights. APM dispute handling varies by scheme and market — some wallets run their own buyer-protection programs, while bank-transfer rails may offer only a recall request. Before adding a method, check what dispute process it actually gives both sides; our recurring payments guide covers how this interacts with stored credentials.
The goal is not to replace cards everywhere. The goal is to offer the methods that remove friction for the customers and markets you actually serve.
Pay by Bank and account-to-account payments
Pay by Bank is a bank-funded checkout flow. The customer pays from a bank account rather than typing card details. Account-to-account, or A2A, is the broader category of direct movement from one bank account to another. The Federal Reserve Pay-by-Bank note describes Pay-by-Bank as a bank-based payment model in which a transaction originates from the customer's bank account and is routed over bank payment rails to the merchant's bank account.
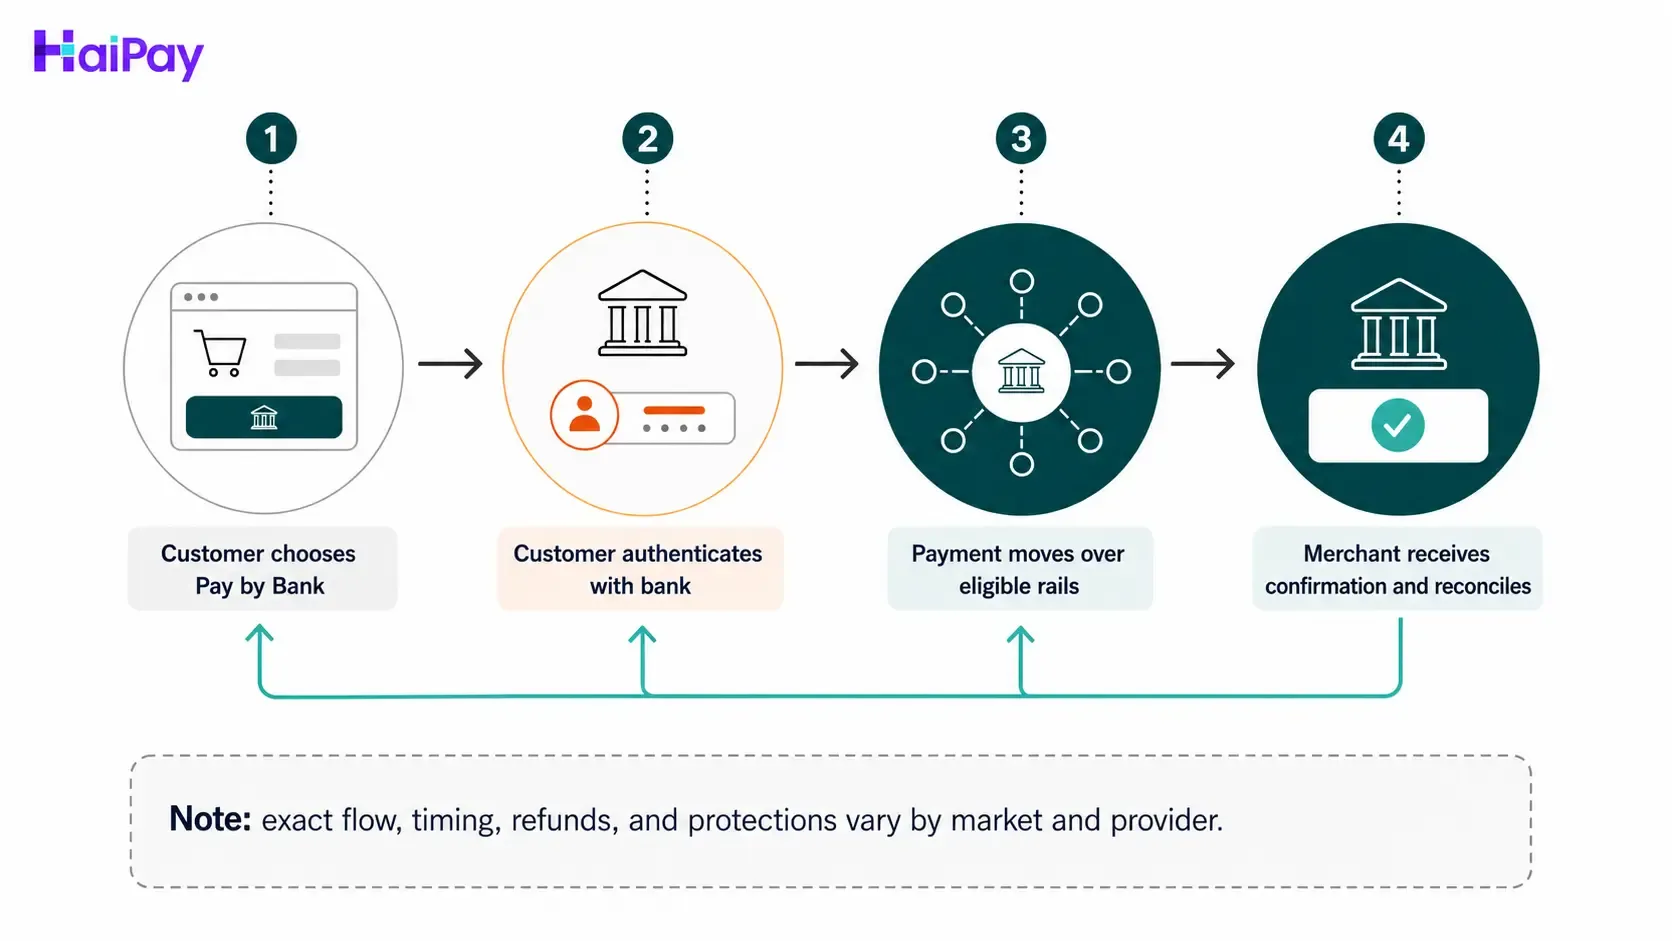
In some markets, Pay by Bank is closely connected to open banking. Open Banking Limited's Pay by Bank guide describes Pay by Bank as a way for customers to pay directly from their bank account, usually by choosing their bank, authenticating, and confirming the payment. It also notes that protections can differ from card payments, so merchants need to understand the specific rule set behind the flow.
For merchants, Pay by Bank can be attractive when customers trust their banking app, when card entry adds friction, or when the business wants a bank-account-funded payment option. But implementation should not start with a generic promise. Start with operational questions:
- Which markets and banks are covered?
- Is the customer redirected, embedded, or asked to scan a code?
- Is confirmation immediate or delayed?
- How are refunds initiated?
- What happens when authentication succeeds but payment confirmation is delayed?
- What support message should a customer see if the payment is pending?
What alternative payment methods cost to accept
APMs are usually priced per transaction, and local payment methods on HaiPay start from 0.8%, priced by market — often below blended card rates. These are published list figures; the rates, fees and minimums that apply to your account are confirmed in your quote.
APM type | Typical fee structure | Relative to cards | Settlement rhythm |
|---|---|---|---|
Digital wallets | Percentage per transaction, priced by market | Often comparable to or lower than blended card rates | Batch settlement, provider-dependent |
Bank transfers / A2A | Low percentage or flat fee per transfer | Usually below card rates — no interchange in the chain | Real-time or same-day confirmation; payout per provider schedule |
Real-time payment networks (UPI, PromptPay, PayNow, Pix-style rails) | Flat or low percentage per transaction | Typically the lowest-cost rail | Instant confirmation to the customer |
Buy now, pay later | Higher percentage than cards, merchant-funded | Above card rates — you pay for conversion lift and credit risk | Provider pays out upfront, keeping its fee |
Crypto / stablecoins | Processor fee plus network cost; conversion fee if settling to fiat | Structure differs — network fees replace interchange | Minutes on-chain; fiat payout adds a conversion step |
Exact rates depend on market and volume — the HaiPay pricing page lists the current per-market structure, and the payment gateway fees guide shows how to compare total cost across providers.
Real-time payment networks
Real-time payment networks such as UPI and Pix are bank-account-based rails that can overlap with A2A and QR payment categories. They should still be evaluated as a separate operational category because confirmation, availability, refunds or returns, reconciliation, and fraud controls depend on the underlying rail.
Cryptocurrency and stablecoin payments
Some payment-industry taxonomies include cryptocurrency and stablecoin payments within alternative payment methods because the customer pays outside the standard card flow. The label is not universal. Merchants should compare the acceptance model, supported assets and networks, exchange-rate handling, settlement currency, refunds, transaction reversibility, wallet screening, AML and sanctions controls, and tax or accounting treatment. Availability and consumer protection vary by jurisdiction. Do not assume that a payment provider supports crypto unless current product documentation confirms it.
Local payment examples to evaluate
The best APM set depends on where your customers are. These examples are not a recommendation to enable every method. They are common method types that teams should evaluate when building a cross-border payment roadmap.
Market signal | Payment examples to evaluate | Why it may matter | Verification required |
|---|---|---|---|
Customers prefer bank-app or QR payment flows | PromptPay and Thai QR-style flows in Thailand | Bank of Thailand describes Thai QR Payment and PromptPay-connected use cases across personal, corporate, e-wallet, and cross-border contexts. | Confirm provider support, customer flow, refund process, settlement, and business eligibility |
Customers use local or regional card brands | JCB in Japan and broader Asia-focused acceptance contexts | JCB positions itself as a major payment brand with a large cardmember and merchant network, especially connected to Asia. | Confirm acquiring support, routing, currency handling, authentication, and dispute rules |
Customers expect domestic wallet or fintech checkout | Naver Pay in South Korea | NAVER describes Naver Pay as a financial platform that includes easy payment and other financial services. | Confirm acceptance model, redirect or app flow, refunds, settlement, and language requirements |
Customers are comfortable paying from bank accounts | Pay by Bank or A2A payments | Bank-based payment flows can reduce card-entry friction when customers trust the bank authentication flow. | Confirm rails, coverage, confirmation timing, refund route, and customer protections |
Customers need deferred payment options | Buy now pay later providers | BNPL can match purchase contexts where installment or deferred payment is part of customer expectation | Confirm provider approval rules, regulated messaging, refund liability, and settlement terms |
Customers prefer cash or offline confirmation | Voucher, convenience-store, or cash-reference payments | Offline flows can help reach customers who do not want to pay by card online | Confirm expiration windows, order reservation rules, payment confirmation timing, and support process |
Alternative payment methods by region: current signals
Payment behavior varies significantly by market. The figures below use different scopes and measurement methods, so they should not be compared as direct APM market-share estimates. Instead, use them as market signals when deciding which payment methods, customer flows, and operational capabilities require further validation.
Region / market | Current data signal | Merchant implication | Source |
|---|---|---|---|
Global / developing markets | In 2024, 42% of adults in low- and middle-income economies made an in-store or online digital merchant payment, up from 35% in 2021. | Do not apply one global payment-method mix to every market. Validate local preferences using checkout analytics, customer research, device behavior, and payment-provider documentation. | |
India / APAC | UPI processed approximately 23.20 billion transactions in May 2026 across 720 live banks. | Verify UPI merchant eligibility, supported banks, INR settlement, QR or app flow, payment confirmation, refunds, reconciliation, and provider coverage before launch. | |
Brazil / LATAM | By the fourth quarter of 2024, Pix accounted for nearly half—47%—of all non-cash payment transactions in Brazil. Pix transaction volume grew by 52% during 2024. | Merchants targeting Brazil should evaluate Pix alongside cards. Confirm merchant eligibility, BRL settlement, QR and account-based flows, instant confirmation, refunds, fraud controls, and reconciliation. | |
Euro area | In the first half of 2025, instant credit transfers accounted for 23% of the total number of credit transfers processed by euro-area retail payment systems. | Verify whether the provider supports SEPA Instant, sending and receiving capabilities, beneficiary verification, IBAN handling, transaction confirmation, fees, refunds, and reconciliation. | |
Sub-Saharan Africa | In 2024, 58% of adults owned a financial account, while mobile-money account use remained at the highest level in the world. | Evaluate mobile money at the country and operator level. Confirm phone-number flows, customer authentication, cash-in and cash-out dependencies, KYC requirements, reversals, settlement currency, and customer support. | |
Middle East and North Africa | Account ownership reached 53% of adults in 2024, up from 45% in 2021. | Treat the region as a group of distinct national markets. Verify local bank and wallet coverage, Arabic-language checkout requirements, customer authentication, KYC, local regulations, settlement, refunds, and consumer-protection rules. |
These figures show why APM selection should begin with market evidence rather than a provider’s full method catalogue. Before enabling a payment method, confirm customer demand, merchant eligibility, currency support, payment flow, settlement, refunds, disputes or reversals, reconciliation, regulatory requirements, and provider availability for the specific market.
If Hong Kong is one of your target markets, use this Hong Kong payment gateway guide to compare gateway, acquiring, settlement, and local-payment requirements.
How to choose the right APMs by market
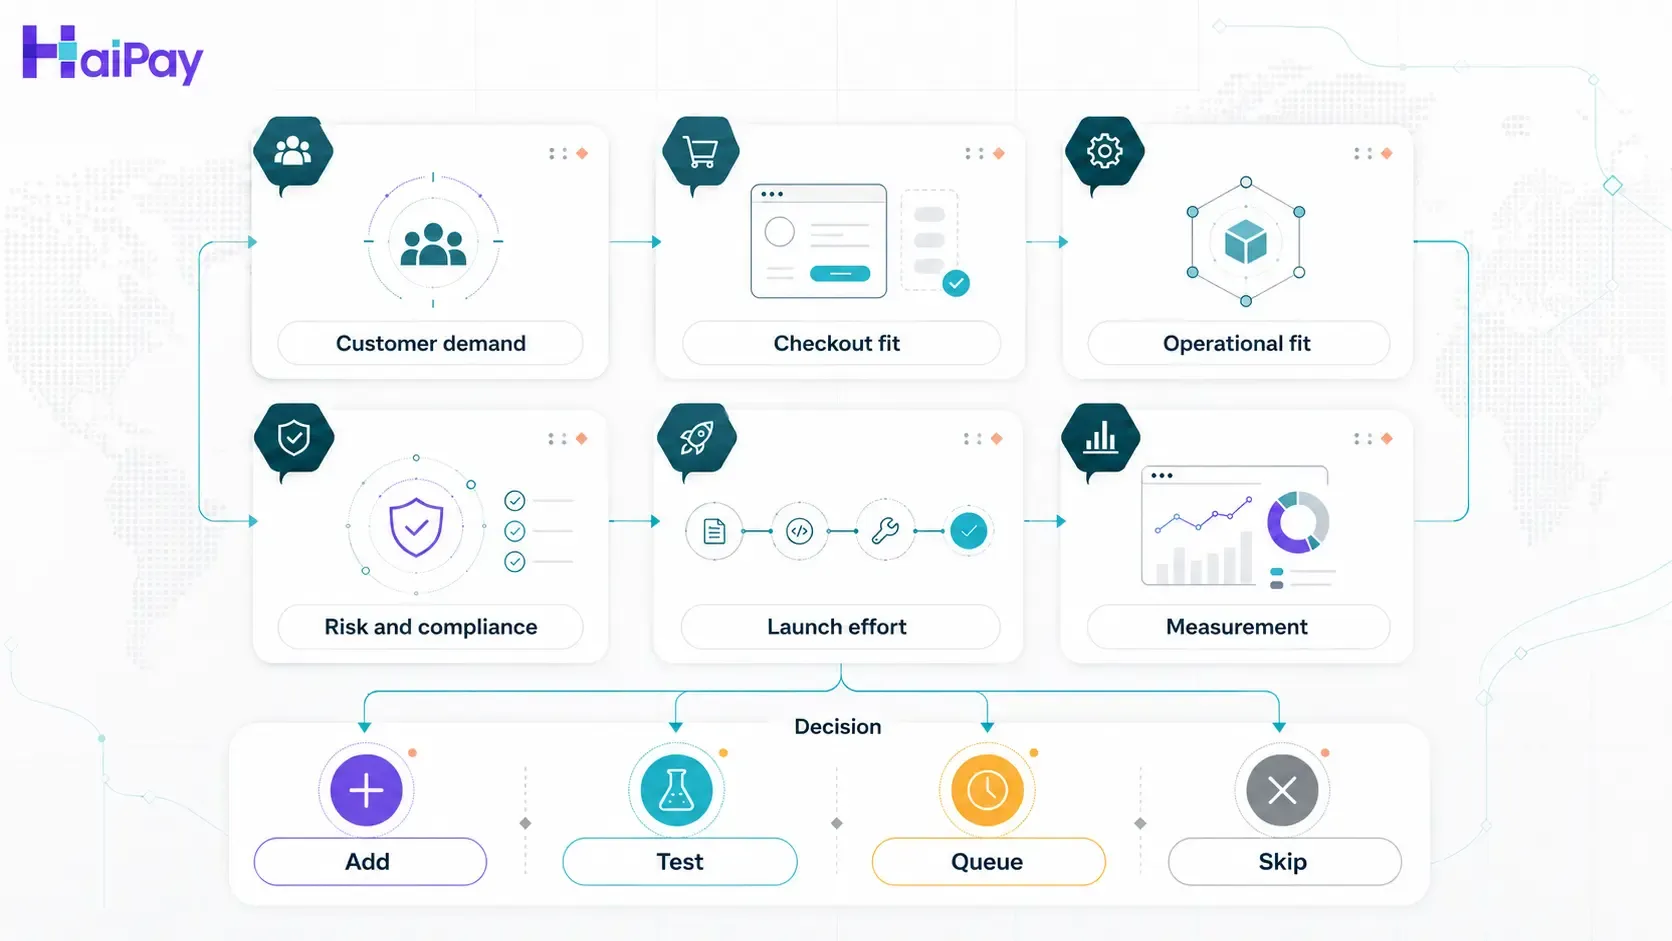
Use a decision matrix before adding payment methods to checkout. The point is to select methods with a clear customer and operational reason.
Decision factor | What to ask | Good signal | Caution signal |
|---|---|---|---|
Customer demand | Do customers in this market already use the method? | Search demand, local competitor adoption, customer interviews, support requests, payment provider guidance | "Competitors have it" is the only reason |
Checkout fit | Does the method match the device, basket size, and purchase context? | Mobile-first method for mobile-heavy market, wallet for repeat consumer checkout, bank-based flow for bank-trusting segment | Long redirect or delayed confirmation for a fast impulse purchase |
Operational fit | Can finance and support handle the payment states? | Clear payment statuses, refund process, reconciliation fields, and support macros | Pending, expired, refunded, and failed states are not mapped |
Risk and compliance | Are the rules understood? | Method-level documentation for authentication, disputes, KYC or merchant-category rules, and regulated messaging | Broad risk-reduction or dispute-elimination promises without source-specific validation |
Launch effort | Is the implementation proportional to the opportunity? | Provider support, test environment, reporting, and market coverage are available | Custom flow needed before demand is proven |
Measurement | Can success be measured? | Baseline conversion, payment-method share, failure rate, refund rate, support tickets, and settlement exceptions | No baseline and no owner for post-launch review |
This is where a checkout provider can help. A provider can simplify method access, hosted checkout design, routing, reporting, and payment-status handling. But each method still needs market, legal, risk, and operational validation before it becomes part of a live checkout.
Explore checkout implementation, then confirm method availability with the HaiPay payments team before making launch commitments.
Method availability can also depend on the acquiring route; compare local acquiring vs cross-border acquiring.
A practical APM rollout plan
Do not launch alternative payment methods as a one-time feature dump. Treat them as a portfolio that should be prioritized, tested, measured, and maintained.
1. Map customer markets and payment expectations
Start with the markets, customer segments, and transaction types that matter most. A merchant selling digital services in South Korea may evaluate different payment methods from a B2B platform expanding into Europe or a marketplace serving mobile-first shoppers in Southeast Asia.
Useful inputs include checkout analytics, abandoned-payment data, support tickets, sales feedback, market research, competitor checkout reviews, and payment provider coverage.
2. Prioritize methods by opportunity and complexity
Score each method against likely demand, coverage, implementation effort, settlement complexity, refund handling, support load, and compliance risk. A method with modest search volume but strong local buyer trust may outrank a globally known method with weak fit for your audience.
3. Design the checkout experience
Customers should understand what will happen when they select a method. If the flow redirects to a bank app, opens a wallet, shows a QR code, creates a pending order, or requires offline payment, the checkout should set expectations before the customer clicks.
Avoid generic labels when a clearer local label exists. Also avoid overloading the payment step with every method at once. Grouping, ordering, localization, and device-aware presentation can matter as much as the methods themselves.
4. Define payment states and support scripts
Every method needs a state model. At minimum, document what your team will show and do for:
- Payment created
- Customer redirected
- Customer authenticated
- Payment pending
- Payment succeeded
- Payment failed
- Payment expired
- Refund initiated
- Refund completed
- Dispute, reversal, or exception
Support teams should know what the customer saw, what status is authoritative, and when to ask payments or finance for help.
5. Confirm settlement, refunds, and reconciliation
Before launch, confirm the operational details with your provider. Do not assume a wallet, bank transfer, local scheme, and BNPL method behave like a card payment after checkout. Settlement timing, fees, refund routes, dispute windows, and reporting fields can differ.
Finance teams should know how each method appears in reports, how fees are represented, how currencies are handled, and how exceptions are investigated.
6. Launch with measurement
Track method adoption and quality after launch. Useful metrics include:
- Payment-method impressions
- Payment-method selection rate
- Authorization or confirmation success rate
- Drop-off after method selection
- Pending-payment completion rate
- Refund rate
- Support contact rate by method
- Settlement exceptions
- Checkout conversion by market and device
APMs should earn their place in checkout. If a method creates more confusion than completed payments, fix the UX, adjust ordering, localize the explanation, or remove it from low-fit segments.
Implementation checklist
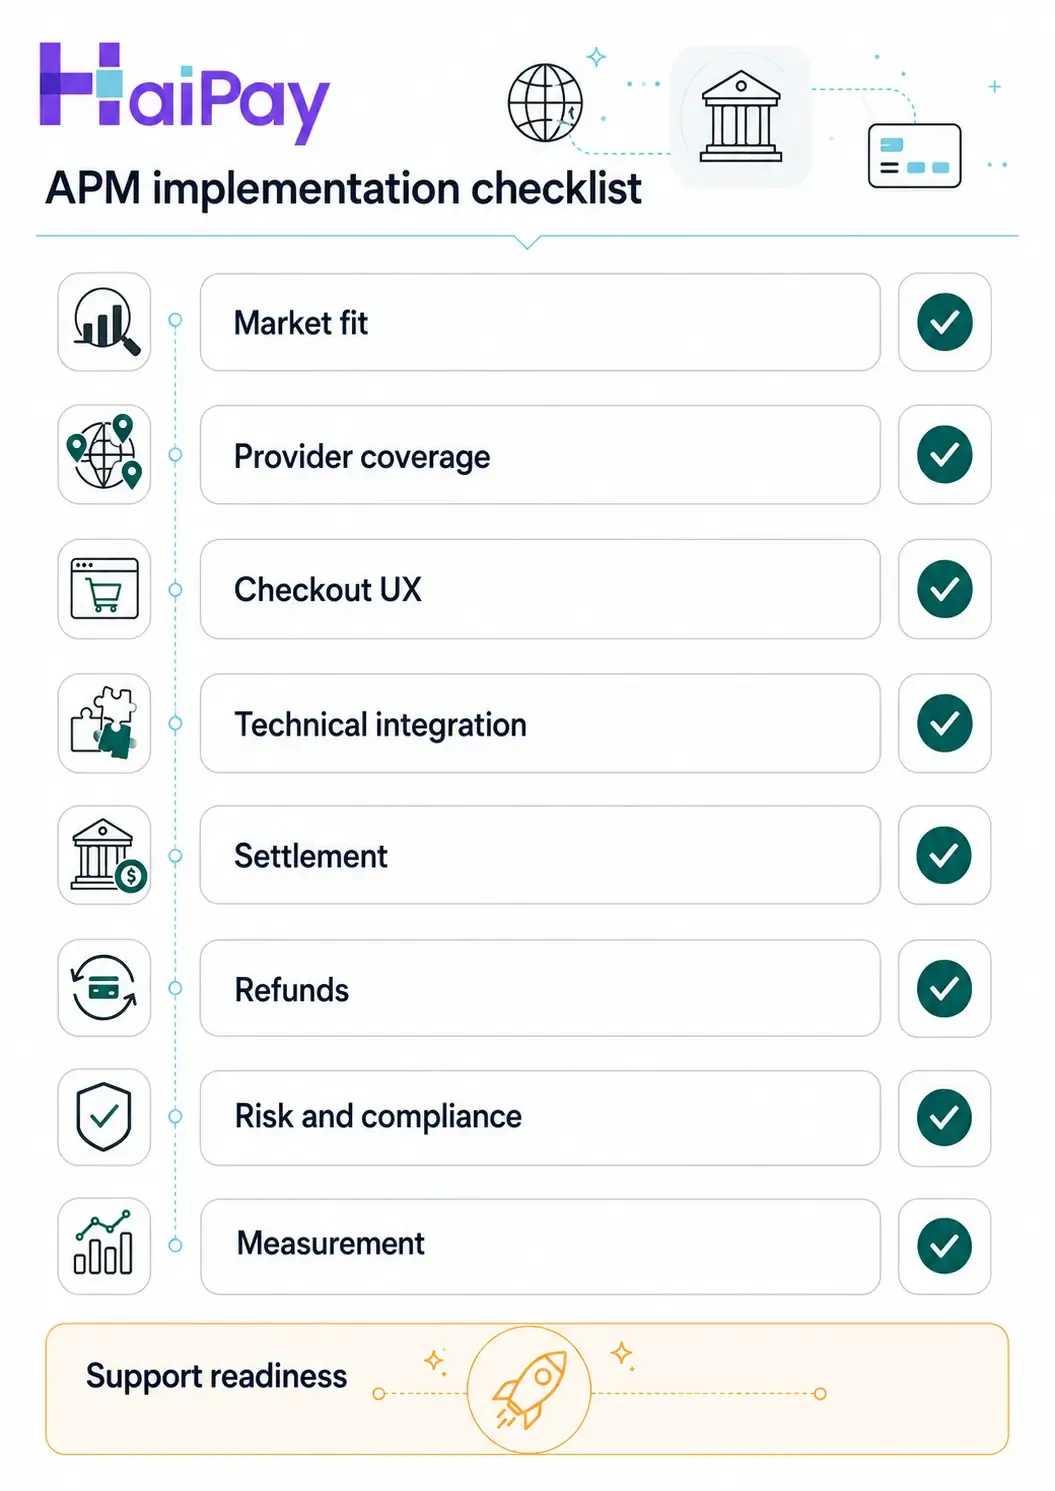
Use this checklist before enabling a new APM.
Area | Checklist item | Owner |
|---|---|---|
Market fit | Identify the target market, segment, and customer reason for the method | Product / Growth |
Provider coverage | Confirm the method is available for the merchant entity, region, currency, category, and customer location | Payments |
Checkout UX | Define label, placement, method grouping, redirect copy, QR copy, pending-state copy, and failure messages | Product / Design |
Technical integration | Confirm API, hosted checkout, webhook, payment-status, idempotency, testing, and fallback requirements | Engineering |
Settlement | Confirm settlement timing, reporting fields, fees, currency handling, and reconciliation workflow | Finance |
Refunds | Confirm refund route, partial refund support, customer notification, timing, and failure handling | Support / Finance |
Risk and compliance | Confirm authentication, dispute or reversal rules, prohibited categories, regulated messaging, and local requirements | Risk / Legal |
Support readiness | Create customer-facing explanations for pending, expired, failed, and refunded payments | Support |
Measurement | Define baseline, launch dashboard, review date, and success threshold | Growth / Analytics |
For HaiPay implementation planning, start from the hosted checkout path, then confirm which methods are available for your markets with the HaiPay payments team. Method availability by market is confirmed in your quote.
When a checkout provider becomes useful
A single payment method can often be integrated directly. A growing cross-border checkout usually needs more structure.
Consider a checkout provider or payment orchestration approach when:
- You sell across multiple countries and need local payment methods.
- You need one checkout experience with market-specific payment options.
- You want reporting and reconciliation across several methods.
- You need to test method ordering, localization, and payment status handling.
- Your support and finance teams need consistent operational workflows.
- You want to add methods without rebuilding the checkout each time.
The provider decision should still be grounded in method coverage, integration quality, payment status clarity, settlement reporting, refund handling, compliance support, and customer experience. A broader method list is useful only if the business can operate it cleanly.
Talk to the payments team to validate the right APM mix for your markets and confirm method availability before implementation.
Common mistakes when adding alternative payment methods
Adding methods without a market reason
A long method list can slow decision-making and make checkout feel less trustworthy. Start with customer demand, not a provider catalog.
Treating every APM like a card payment
APMs can differ in confirmation timing, refunds, disputes, reversals, reporting, and customer communication. Build method-specific operating notes before launch.
Ignoring pending and expired payment states
Some methods may not complete in a single immediate authorization flow. If the customer leaves checkout, scans a code, pays offline, or confirms in a bank app, your system and support team need a clear status model.
Making unverified regional claims
"Popular in Asia" or "best for Europe" is too vague to be useful. Use market-specific research, provider documentation, and internal performance data.
Measuring only total conversion
Track method selection, drop-off after selection, payment success, pending completion, refunds, and support tickets. A method may improve trust for one segment while creating friction for another.
Next step
Build the APM roadmap around the markets you serve, the customers you want to convert, and the operations your team can support. Then validate the method list with your provider before implementation.
- Explore hosted checkout options
- Talk to the payments team to confirm the right payment mix for your business.
Sources
Sources checked on 9 September 2026.
World Bank, Mobile phone technology powers saving surge in developing economies (Global Findex 2025 press release). Release dated 16 July 2025. Digital merchant payment adoption, account ownership, and mobile-money signals used in the definition section and the regional table.
Federal Reserve Board, FEDS Notes, Pay-by-Bank and the Merchant Payments Use Case: Benefits, risks and potential impacts on consumer payment behaviors in the U.S.. Note dated 7 July 2025. Definition of the Pay-by-Bank model used in the Pay by Bank section.
Open Banking Limited, Pay by Bank. Customer flow and how protections can differ from card payments in the UK.
Bank of Thailand, PromptPay. Thai QR Payment and PromptPay use-case context; not evidence of any provider's merchant support.
JCB, What We Do. Brand positioning and network scope; acquiring support must be confirmed with the provider.
NAVER Corp., Fintech services (Naver Pay) (page in Korean). Description of Naver Pay as a financial platform with easy-payment services.
NPCI, UPI Product Statistics. Monthly UPI transaction volume and live-bank count cited in the regional table.
Banco Central do Brasil, Press note on Pix (2024 figures). Pix share of non-cash payment transactions and 2024 volume growth.
European Central Bank, Payment statistics: first half of 2025. Instant credit transfer share of euro-area credit transfers.
FAQ
Examples include digital wallets, Pay by Bank and other account-to-account payments, bank transfers, direct debit, buy now pay later, QR payments, local card schemes, vouchers, cash-reference payments, real-time payment networks, cryptocurrency and stablecoin payments where supported, and domestic fintech payment options. The right examples depend on the target market and customer segment.
Not exactly. A2A is the broader category of account-to-account payment movement. Pay by Bank is a checkout experience that lets a customer pay from a bank account, often through bank authentication, open banking, or bank-based payment rails depending on the market and provider.
Generally yes — most authenticate in the customer's own bank or wallet app, which removes the shared-card-number risk. The trade-off is on the merchant-operations side: push-based APMs settle with finality, and dispute frameworks vary by method, so verify the reversal and dispute process for each method you add.
Usually no. Cards remain important in many markets. APMs should complement cards when they improve customer trust, local relevance, or payment completion for a specific segment.
Enough to match customer expectations without cluttering the payment step. Start with the markets and customer segments that drive revenue, then prioritize methods by demand, operational readiness, and measurable impact.
Start with the methods that match your top customer markets. For example, evaluate Pay by Bank where bank-account-funded checkout is relevant, local wallets where wallet usage is expected, local card schemes where they carry customer trust, and QR or voucher flows where they fit the market. Confirm provider support and operational rules before launch.
Evaluate each one as a market-specific method rather than as a generic global APM. PromptPay is connected to Thailand's bank and QR payment ecosystem. JCB is a major card brand with Asia-focused relevance. Naver Pay is a South Korea-focused financial platform with easy-payment functionality. Confirm acceptance, settlement, refunds, customer experience, and provider support before adding any of them.

Related HaiPay surfaces
Explore the payment stack
Product
Local Payment Methods
Explore local payment method coverage and checkout integration options for businesses expanding across international markets.
Guide
International Payment Gateway
Compare international gateway options by eligibility, payment methods, currencies, settlement, integrations, and operational fit.
Guide
Local Acquiring vs Cross-Border Acquiring
Compare local and cross-border acquiring by merchant entity, routing, settlement, acceptance, and operational trade-offs.

Need help mapping your payment stack?
Talk to HaiPay about acquiring, orchestration, local methods, and payout workflows.
Contact us